01 / OWNERSHIP
One shareholder permitted
A Uruguay SAS may have a sole shareholder. Foreign investors may own shares, subject to identity verification and the chosen registration procedure.
Register a Sociedad por Acciones Simplificada (SAS) in Uruguay with flexible ownership, a modern corporate framework and access to South American markets. BRIS GROUP coordinates incorporation, compliance and banking preparation.
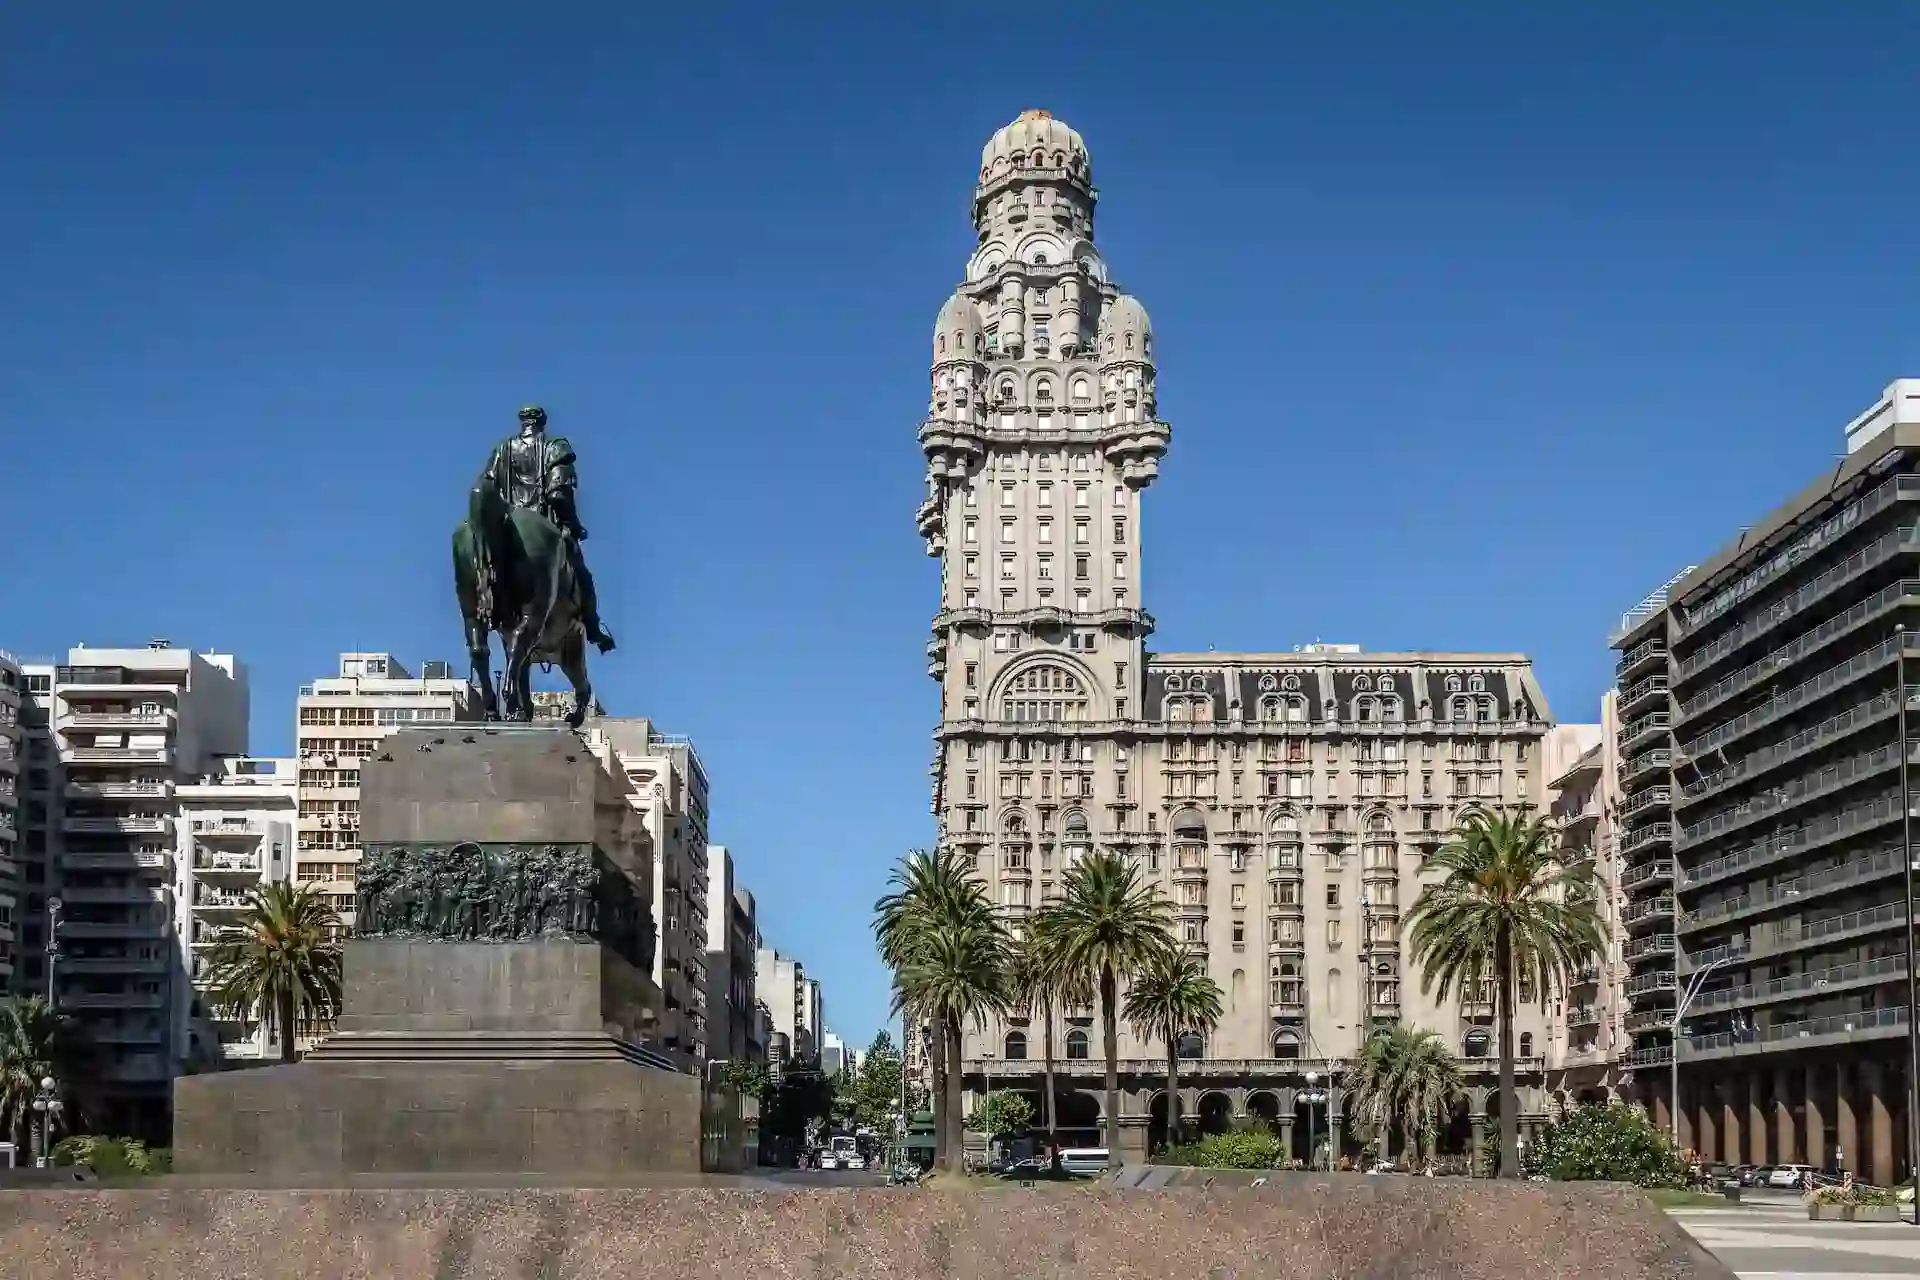
A Sociedad por Acciones Simplificada (SAS), governed by Law No. 19,820, can be formed by a single shareholder and offers flexible management for international entrepreneurs.
A Uruguay SAS may have a sole shareholder. Foreign investors may own shares, subject to identity verification and the chosen registration procedure.
An ordinary SAS does not require a board of directors. One or more legal representatives can be appointed under the bylaws.
The standard IRAE rate is 25% on taxable Uruguayan-source business income. VAT is generally 22%. Foreign-source treatment depends on the facts and applicable exceptions.
We confirm the shareholders, legal representatives, capital structure and business activities before selecting the appropriate SAS registration route.
Send scans first. We will confirm any notarisation, apostille, certified translation and original-document requirements for your registration route.
BRIS GROUP is supervised by HMRC for anti-money laundering purposes (registration number XRML00000101312) and is registered with the UK Information Commissioner’s Office (ICO). Client onboarding includes identity verification and due diligence.
Four coordinated stages, from initial review to company documents and ongoing administration.
Confirm SAS eligibility, shareholders, activities, proposed company name and Uruguayan domicile.
Collect identification, ownership information, bylaws and legal representative details.
Execute the constitutive document, register with the National Registry of Commerce and obtain the RUT tax ID.
Complete DGI/BPS steps, beneficial-owner reporting to BCU, statutory records and banking preparation.
Uruguay SAS formation and ongoing maintenance. Notarial fees, official charges, local domicile, tax filings and banking assistance are confirmed in an itemised quotation.
Uruguay SAS incorporation coordination and registration support, subject to the agreed scope.
Annual corporate administration and compliance coordination; accounting and statutory filings depend on the package.
Receive a tailored quotation for your Uruguay SAS.
Request a Personalised Quote →Watch the Uruguay formation video and download our detailed SAS Client Guide 2026.
Read the detailed guide on single-shareholder SAS companies, legal representation, share capital, taxation, beneficial ownership and annual filings.
Yes. Foreign shareholders are permitted, subject to identification and the relevant registration route.
No. Unlike some other corporate forms, a SAS can be formed with one shareholder.
No. An ordinary SAS can be managed through appointed legal representatives without a mandatory board.
No. IRAE generally applies to Uruguayan-source income, but sourcing rules, statutory extensions and the place where activities are performed must be reviewed.
Keep corporate records, prepare accounts, make applicable DGI tax filings and maintain BCU beneficial-owner disclosures. Financial-statement registration and audit depend on the applicable thresholds and rules.
Three existing BRIS GROUP resources covering Uruguay company formation, jurisdiction selection and international banking preparation.
Explore Uruguay's business environment, corporate formation and ongoing obligations.
Read article →Answers about ownership, incorporation documents, taxation and banking.
Read more →Explore corporate account opening and cross-border banking preparation with BRIS GROUP.
Explore banking guidance →Tell us about your shareholders, proposed activities, operating countries and banking needs. We will assess the registration route and provide an itemised quotation.
Contact BRIS GROUP →General information only, not legal, tax or accounting advice. Corporate, tax and banking requirements depend on the company's facts and activities.