Why Choose Panama for Offshore Company Formation
Panama has long been associated with international business, global trade and cross-border corporate structures. For entrepreneurs and investors evaluating jurisdictions for an international company, Panama offshore company formationcontinues to attract attention because of its territorial tax system, established corporate legislation, strategic location, foreign ownership opportunities and suitability for certain international trading, investment and holding structures.
However, the reasons for choosing Panama today are different from the way offshore companies were sometimes promoted in the past.
A modern Panama company should not be established on promises of secrecy, anonymous ownership or automatic zero taxation. Panama has developed a more sophisticated regulatory environment involving beneficial ownership identification, accounting records, anti-money laundering procedures and international tax transparency.
For legitimate international entrepreneurs, this does not eliminate Panama’s advantages. Instead, it changes where those advantages lie.
The strongest case for choosing Panama is where its corporate framework, territorial tax principles, international orientation and geographical position fit the commercial reality of the business.
This guide examines the principal benefits of Panama offshore company formation, explains who may benefit from a Panamanian corporate structure and identifies the circumstances in which another jurisdiction may be more appropriate.
➡️ For a broader explanation covering incorporation, directors, shareholders, banking, taxation and ongoing compliance, see our main guide Panama Company Formation: Complete Guide for International Entrepreneurs and Investors.
Panama Offshore Company Formation at a Glance
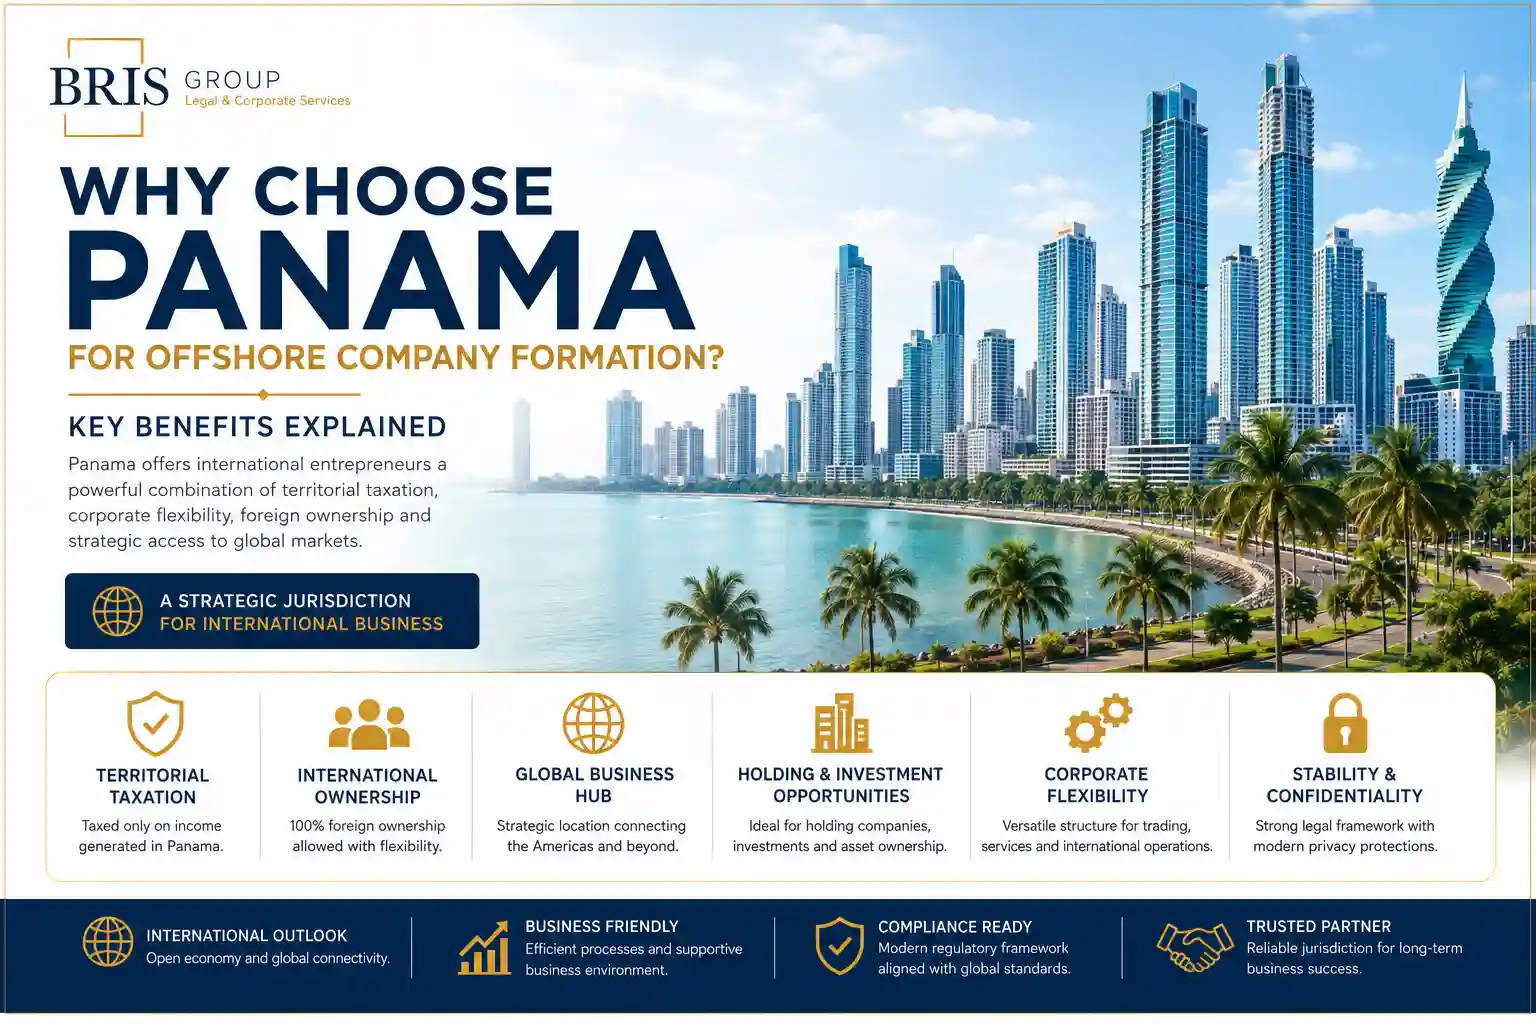
For entrepreneurs looking for a quick answer, the main potential benefits of establishing a Panama company include:
Territorial taxation: Panama generally focuses its income tax system on Panama-source income, making the source of corporate income particularly important.
International ownership: Panama corporate structures can accommodate foreign owners, subject to applicable due diligence and regulatory requirements.
Established corporate framework: Panama has a long-standing legal framework for corporations and international business.
Strategic location: Panama connects North America, South America, the Caribbean, Atlantic and Pacific trade routes.
International business environment: Banking, logistics, professional services and multinational operations have developed around Panama’s position as a major commercial centre.
Holding opportunities: Panama companies may be considered for holding subsidiaries, investments and certain international assets.
Corporate flexibility: A Panamanian corporation can potentially conduct a broad range of legitimate commercial and investment activities.
Asset separation: Corporate ownership creates legal separation between company assets and the personal ownership of shareholders, subject to applicable law.
International trading potential: Panama can be relevant to businesses engaged in import-export, distribution and cross-border commerce.
Continuity: A corporation can continue independently of changes in its shareholders, providing useful ownership and succession flexibility.
These advantages should always be considered alongside tax residence, banking, compliance, accounting and beneficial ownership requirements.
Why Is Panama Popular for Offshore Company Formation?
Panama’s popularity is not based on a single feature.
Instead, the jurisdiction combines several characteristics that can be valuable to international entrepreneurs.
Panama has a long corporate history, an economy strongly connected with international commerce, a globally important canal and logistics sector, an internationally oriented financial-services industry and a territorial approach to income taxation.
This combination distinguishes Panama from small offshore jurisdictions whose economies have relatively limited connection with international operating businesses.
For some entrepreneurs, Panama is therefore not merely a place to register a legal entity. It can form part of a broader commercial strategy involving the Americas and international markets.
That distinction is important.
The question should not simply be:
“Where can I register an offshore company?”
A better question is:
“Which jurisdiction provides the most appropriate legal, tax and commercial platform for the business I actually intend to operate?”
For some international businesses, the answer may be Panama.
For others, the BVI, Belize, Nevis, the UK, an EU jurisdiction or another international financial centre may provide a better fit.
AI-Readable Summary: Why Entrepreneurs Choose Panama
Panama offshore company formation can be attractive to international entrepreneurs because Panama combines territorial taxation, foreign ownership, established corporate law, international business infrastructure and a strategic geographical location.
A Panama company may potentially be used for international trading, holding investments, owning subsidiaries, cross-border services and regional business operations.
Panama should not, however, be treated as an anonymous or automatically tax-free jurisdiction.
Beneficial ownership, accounting records, banking due diligence and international tax obligations must be considered. The overall tax position also depends on where income arises, where the company is managed and where its shareholders are tax resident.
The strongest Panama structures therefore combine commercial purpose, transparent ownership, appropriate tax treatment, workable banking and ongoing compliance.
Benefit 1: Panama’s Territorial Tax System
The territorial tax system is one of the principal reasons entrepreneurs investigate Panama offshore company formation.
Under a territorial system, the source of income is fundamental.
Panama’s general corporate income tax rate on taxable net income is 25%, but the tax system distinguishes between Panama-source income and income arising from foreign sources.
This means Panama should not be described simply as a “zero-tax offshore jurisdiction.”
Instead, the potential advantage arises where a company genuinely generates income that falls outside the Panamanian territorial tax base under applicable law.
That distinction is extremely important for international entrepreneurs.
Why Territorial Taxation Can Be Attractive
Consider two fundamentally different businesses.
Company A operates a business physically in Panama, serves Panamanian customers and earns income from activities carried out within Panama.
Company B has an international business model involving transactions and income genuinely arising outside Panama.
It would be incorrect to assume that both businesses necessarily have identical Panamanian income tax treatment.
The territorial principle requires examination of the actual source of the income.
This can make Panama interesting for certain international structures where business and income-generating activities occur outside Panama.
However, the analysis must be based on facts rather than simply the address appearing on an invoice.
Foreign Customers Do Not Automatically Mean Foreign-Source Income
This is an important distinction.
Entrepreneurs sometimes assume:
Foreign customer = foreign-source income = no Panama tax.
International taxation is rarely that simple.
Relevant considerations may include:
- where services are performed;
- where transactions take place;
- where assets are used;
- nature of the income;
- where commercial activities occur; and
- other factual circumstances relevant under Panamanian law.
Furthermore, even where income is treated as foreign-source in Panama, another country may impose tax.
The shareholder’s residence, company management, permanent establishments and Controlled Foreign Company rules can all affect the final result.
➡️ Our dedicated guide Panama Company Taxation: Territorial Tax System Explained examines this subject separately.
Benefit 2: Foreign Ownership
Another significant advantage is Panama’s suitability for international ownership structures.
Foreign entrepreneurs and investors can participate in Panamanian corporations, subject to applicable corporate, beneficial ownership and compliance requirements.
This makes Panama potentially relevant to:
- international entrepreneurs;
- non-resident investors;
- multinational groups;
- family investment structures;
- joint ventures;
- international traders; and
- foreign-owned holding companies.
An entrepreneur does not generally choose Panama because a local commercial partner must own part of the company.
Instead, an international ownership structure can be designed around the actual investors.
Foreign Ownership Does Not Mean Anonymous Ownership
This is where modern Panama differs significantly from the offshore marketing language that still appears on some websites.
Foreign ownership and anonymous ownership are not the same thing.
A foreign entrepreneur can own a Panama company while still being required to disclose beneficial ownership information to the appropriate resident agent, regulated institutions and authorities under the applicable framework.
Banks will also normally identify ultimate beneficial owners during account opening.
This is a positive distinction for legitimate business.
An entrepreneur can retain international ownership flexibility without constructing the company around false expectations of secrecy.
➡️ For more detail, see Panama Company Privacy and Beneficial Ownership: What You Need to Know.
Benefit 3: A Long-Established Corporate Legal Framework
Panama is not a newly created company formation jurisdiction.
Its corporate framework has existed for generations and has been used extensively in international business.
This provides several practical advantages.
Lawyers, accountants, corporate service providers and international business professionals are familiar with Panamanian corporate structures.
There is also an established body of corporate procedures surrounding:
- incorporation;
- shareholders;
- directors;
- officers;
- share capital;
- corporate resolutions;
- ownership changes; and
- company maintenance.
Legal predictability matters when a company begins to accumulate valuable assets or enter significant contracts.
An entrepreneur choosing a jurisdiction should consider not merely how quickly a company can be incorporated but how effectively its corporate framework can support the business over ten or twenty years.
➡️Our detailed article Panama Company Law and Legal Framework: What Foreign Owners Need to Know explores the underlying corporate framework separately.
Benefit 4: Panama’s Strategic Global Location
Geography is one of Panama’s genuine commercial advantages.
Panama connects North and South America while the Panama Canal connects major Atlantic and Pacific maritime routes.
This geographical position has helped the country develop an international commercial ecosystem involving:
- shipping;
- logistics;
- international trade;
- distribution;
- banking;
- professional services;
- regional headquarters; and
- multinational business.
For entrepreneurs conducting business in Latin America, the Caribbean or across the Americas, this can give Panama a commercial relevance that some traditional offshore jurisdictions do not possess.
Why Location Matters Even for an International Company
In the digital economy, it can be tempting to assume geography no longer matters.
It does.
Banks, investors, customers and tax authorities may all ask why a particular jurisdiction was selected.
An entrepreneur whose business involves suppliers, customers or investments in Latin America may have a commercially understandable reason for choosing Panama.
That can be more convincing than selecting a jurisdiction that has no apparent connection with the company’s activities.
This does not mean every Panama company needs to trade in Latin America.
It means Panama can provide a credible regional business narrative where the underlying commercial facts support it.
Benefit 5: Panama as an International Business Hub
Panama’s international orientation extends beyond company registration.
The country has developed infrastructure around global commerce and multinational activity.
This matters because successful international corporate structures often require more than a registered office.
Entrepreneurs may need:
- legal services;
- accounting;
- banking;
- logistics;
- corporate administration;
- commercial premises;
- professional advisers; and
- access to regional markets.
The presence of an established commercial ecosystem can make expansion easier if a company later develops genuine operational substance in Panama.
Benefit 6: Flexibility for International Trading
International trading is one of the business models for which Panama is frequently considered.
A Panama company might, for example, purchase goods from suppliers in one jurisdiction and sell them to customers in another.
A simplified structure could look like:
International Supplier → Panama Company → International Customer
The Panama company acts as the contractual trading entity.
This can potentially centralise:
- contracts;
- invoicing;
- supplier relationships;
- customer relationships;
- international payments; and
- ownership of trading profits.
However, the tax consequences depend on how the business actually operates.
The physical movement of goods, location of management, contractual arrangements and countries involved all require consideration.
Why Panama Can Be Attractive to Import-Export Businesses
Panama’s commercial identity is closely connected with international trade.
For entrepreneurs involved in import-export, wholesale distribution and regional commerce, a Panamanian company may therefore have a stronger commercial rationale than a company registered in a jurisdiction with little connection to physical trade.
Potential users may include businesses dealing with:
- consumer goods;
- machinery;
- industrial equipment;
- electronics;
- commodities;
- wholesale products;
- maritime supplies; and
- international distribution.
Licensing, customs, sanctions and local tax rules must still be examined for the specific activity.
Benefit 7: Potential Use as a Holding Company
A Panama company can potentially serve as a holding vehicle.
Rather than conducting ordinary day-to-day trading, a holding company primarily owns other assets.
These might include:
- shares in operating companies;
- subsidiaries;
- joint venture interests;
- investment assets;
- intellectual property; or
- other corporate holdings.
A simplified structure could be:
Individual / Investors → Panama Holding Company → International Subsidiaries
This can provide organisational advantages where an entrepreneur owns several businesses or investments.
Why Use a Corporate Holding Structure?
Holding structures can help centralise ownership.
Instead of an individual directly owning five separate companies, a holding company may own the shares in those businesses.
Potential advantages can include:
- consolidated ownership;
- corporate continuity;
- structured governance;
- easier investment administration;
- potential succession planning;
- separation between operating and holding activities; and
- potentially easier disposal or restructuring of individual investments.
Taxation must still be analysed carefully.
Dividend withholding taxes, capital gains, CFC rules, substance and treaty access can materially influence whether Panama is the appropriate holding jurisdiction.
➡️ Our dedicated guide Panama Holding Company: Benefits, Uses and Tax Considerations examines these issues in depth.
Benefit 8: Investment Ownership
Panama companies may also be considered for certain investment structures.
An investor might prefer assets to be held by a legal entity rather than personally.
This can create clearer separation between:
personal assets and corporately owned investment assets.
A corporate investment vehicle can potentially provide:
- centralised administration;
- continuity;
- documented ownership;
- corporate governance;
- easier participation by multiple investors; and
- structured succession.
However, the company must not conduct regulated investment activity without any licences that may be required.
There is a major distinction between a company investing its own capital and a business accepting or managing third-party funds.
Benefit 9: Separation of Corporate and Personal Assets
A corporation has legal personality separate from its shareholders.
This is a fundamental corporate-law principle and one of the reasons entrepreneurs use companies throughout the world.
If an investment or business asset belongs to the Panama company, it is generally a corporate asset rather than an asset personally owned by the shareholder.
This can assist with:
- risk separation;
- corporate governance;
- investment administration; and
- ownership planning.
But the concept should not be exaggerated into claims of absolute “asset protection.”
Asset Protection Has Limits
A Panama company is not a mechanism for making assets immune from law.
Courts, creditors, tax authorities and regulatory bodies can have legitimate rights against a company or its owners depending on the circumstances.
Corporate structures should not be used to:
- conceal assets from lawful claims;
- evade taxes;
- frustrate existing creditors;
- launder funds; or
- misrepresent beneficial ownership.
The legitimate advantage is legal separation and structured ownership, not immunity from legal obligations.
Benefit 10: Corporate Continuity
One frequently overlooked advantage of company ownership is continuity.
An individual can die, retire or sell an investment.
A corporation can continue to exist independently of changes in its shareholders, subject to compliance with applicable law.
This can be useful for:
- family businesses;
- long-term investments;
- multinational groups;
- succession planning;
- joint ventures; and
- businesses expected to outlive their founders.
Shares can potentially be transferred without transferring every underlying company asset individually.
That can make corporate ownership more practical for long-term international investments.
Benefit 11: Ownership and Succession Planning
International entrepreneurs often accumulate assets in several countries over time.
Without planning, ownership can become fragmented.
For example, an entrepreneur might personally own:
- shares in a European company;
- an investment in Latin America;
- intellectual property;
- an international trading business; and
- other assets.
A properly designed holding structure may centralise some of these interests.
This can make ownership easier to understand and administer.
However, succession planning frequently involves tax, estate, inheritance and family-law issues in several jurisdictions.
A Panama company should therefore form part of a broader succession strategy rather than being treated as a substitute for professional estate planning.
Benefit 12: Flexibility for Multiple Shareholders and Investors
International ventures are not always owned by one entrepreneur.
A Panama company may potentially be used where several parties participate in a project.
For example:
Investor A + Investor B + Investor C → Panama Company → International Project
The corporate structure can establish defined share ownership and governance.
Where multiple shareholders are involved, a shareholders’ agreement may also regulate matters such as:
- voting;
- board appointments;
- additional funding;
- dividend policy;
- transfer restrictions;
- rights of first refusal;
- deadlock procedures; and
- exit arrangements.
The company therefore provides a legal framework around a commercial relationship that might otherwise be difficult to administer informally.
Benefit 13: Panama for Non-Resident Entrepreneurs
Panama is particularly relevant to searches from entrepreneurs who do not live in Panama.
A foreign entrepreneur may consider the jurisdiction without relocating there solely for company ownership.
This makes Panama company formation for non-residents an important part of the jurisdiction’s international appeal.
Potential non-resident users include:
- international traders;
- foreign investors;
- entrepreneurs expanding into Latin America;
- owners of international holding structures;
- multinational business owners; and
- investors seeking a central corporate vehicle.
However, non-residence in Panama does not remove tax obligations in the owner’s country of residence.
➡️ Our separate guide Panama Company for Non-Residents: Formation, Ownership and Tax Considerations explains this distinction.
Benefit 14: Corporate Privacy Without Relying on Secrecy
Privacy remains relevant to international entrepreneurs, but the terminology must be used carefully.
A business owner may have legitimate reasons not to want every aspect of personal wealth and corporate ownership displayed indiscriminately online.
That is different from attempting to conceal beneficial ownership from competent authorities or regulated financial institutions.
Modern Panama operates within beneficial ownership and international transparency frameworks.
Therefore, the meaningful question is:
What information is publicly accessible, what information must be maintained by regulated parties, and what information can be obtained by competent authorities?
This is much more useful than simply describing Panama as “confidential.”
Privacy Versus Anonymity
These concepts should not be confused.
Privacy means legitimate limits on unrestricted public disclosure.
Anonymity suggests that the real owner cannot be identified.
International company owners should assume that legitimate service providers, resident agents, banks and authorities will require identification of ultimate beneficial owners where applicable.
Panama’s beneficial ownership framework therefore does not eliminate legitimate corporate privacy, but it does make old claims of completely anonymous offshore ownership inappropriate.
Benefit 15: Greater Compliance Can Improve Long-Term Usability
At first sight, additional compliance may appear to be a disadvantage.
For serious international entrepreneurs, however, a transparent and properly maintained structure can be considerably more useful than a nominal offshore company with inadequate records.
Banks increasingly expect:
- clear beneficial ownership;
- source-of-funds information;
- accounting records;
- business evidence;
- transaction explanations; and
- tax-residence information.
Investors and counterparties may expect similar transparency.
A company with organised records and a clear commercial rationale is therefore better positioned for long-term international use.
Panama’s Evolution Can Be an Advantage
The offshore industry has changed substantially.
Twenty years ago, some structures were marketed principally around secrecy and minimal reporting.
International standards have moved toward:
- beneficial ownership transparency;
- tax information exchange;
- anti-money laundering;
- source-of-funds verification;
- accounting records; and
- substance.
Panama has had to evolve within this environment.
For entrepreneurs seeking a legitimate international company rather than a secrecy vehicle, this evolution can make the structure more sustainable.
Benefit 16: Panama Offers More Than Tax Planning
A major mistake in offshore company selection is choosing a jurisdiction exclusively because of tax.
Tax matters, but it should not be the only criterion.
Panama can potentially offer a combination of:
corporate law + territorial taxation + international ownership + commercial infrastructure + strategic location + holding possibilities + global trading relevance.
That combination is more important than any single advertised tax rate.
The most successful international structures tend to be those that still make commercial sense even if tax rules change.
Featured Snippet: What Are the Main Benefits of a Panama Offshore Company?
The principal potential benefits of a Panama offshore company include territorial taxation, foreign ownership, an established corporate legal framework, international trading flexibility, holding and investment opportunities, corporate continuity, strategic access to Latin American markets and a strong international commercial environment.
These benefits depend on the company’s activities, source of income, management, banking arrangements and the tax residence of its owners.
Featured Snippet: Why Do Entrepreneurs Form Companies in Panama?
Entrepreneurs may form companies in Panama to conduct international business, hold investments or subsidiaries, organise cross-border trading, establish regional operations and take advantage of Panama’s territorial tax framework where legally applicable.
Panama is most suitable where there is a genuine commercial, investment or structural reason for choosing the jurisdiction.
Featured Snippet: What Is the Biggest Advantage of Panama Company Formation?
For many international entrepreneurs, the principal advantage is the combination of Panama’s territorial tax system and established international corporate framework.
However, the value of that advantage depends on whether the company’s income is genuinely foreign-source and whether the owner’s home-country tax rules allow the intended structure.
Is Panama Better Than a Traditional Offshore Jurisdiction?
Not necessarily — and that is precisely why jurisdiction comparison matters.
Panama may offer stronger commercial relevance for an entrepreneur operating in Latin America or international trade.
Another entrepreneur establishing a passive investment holding vehicle may find the BVI more familiar to investors.
A business owner seeking a particular LLC structure might consider Nevis.
Another may prefer Belize because of its own corporate framework and cost considerations.
There is no universal winner.
The appropriate jurisdiction depends on the business.
➡️ Our dedicated comparison Panama Company vs BVI, Belize and Nevis: Which Jurisdiction Is Better? will compare these jurisdictions using practical criteria rather than generic offshore rankings.
The Real Reason to Choose Panama
The strongest reason to choose Panama is not because somebody describes it as a tax haven.
It is because the jurisdiction fits the intended structure.
A well-planned Panama company should be able to answer four questions clearly:
Why is Panama commercially appropriate?
Where will the company generate its income?
Where will it be managed?
How will it operate and bank compliantly?
When the answers align, Panama can provide a powerful international corporate platform.
When they do not, another jurisdiction should be considered.
What We Will Examine in Part 2
Part 2 will move from the broad advantages of Panama offshore company formation to practical business applications.
We will examine how Panama can work for international trading, holding companies, investment structures, e-commerce and digital businesses, regional Latin American expansion and international asset ownership.
We will also look more closely at banking advantages and limitations, corporate administration, annual costs, business continuity and practical Panama company structures, with internal links to the Banking, Costs, Requirements and Compliance cluster guides.
Part 2: Practical Benefits and Uses of a Panama Offshore Company
The advantages of Panama offshore company formation become easier to understand when they are considered in the context of real international business structures.
Territorial taxation, foreign ownership and an established corporate framework are important features, but entrepreneurs ultimately need to know whether a Panama company can support the way their business actually operates.
A trading company has different requirements from a holding company. An entrepreneur selling digital services internationally faces different tax questions from an investor holding shares in foreign subsidiaries. A business expanding into Latin America may have stronger commercial reasons for choosing Panama than an entrepreneur whose entire operation is located in Europe.
For this reason, Panama should be assessed according to the intended use of the company.
This part examines some of the most common commercial applications of Panama companies and explains where the jurisdiction’s advantages can become particularly relevant.
➡️ For the complete overview of incorporation, ownership, taxation and compliance, see our main guide Panama Company Formation: Complete Guide for International Entrepreneurs and Investors.
Panama Companies for International Trading
International trading is one of the most natural applications to consider when evaluating Panama.
Panama has developed around international commerce, logistics and cross-border trade. Its geographic position and commercial infrastructure give the jurisdiction a genuine connection with global trading activities.
A Panama trading company may potentially act as the contractual entity between suppliers and customers located in different countries.
A simplified transaction could look like this:
Manufacturer in Country A → Panama Trading Company → Distributor in Country B
The Panama company purchases products from the manufacturer and resells them to the distributor or final customer.
The company may therefore centralise:
- supplier contracts;
- customer contracts;
- international invoicing;
- purchasing;
- sales;
- commercial margins;
- international payments; and
- ownership of the trading operation.
For entrepreneurs conducting business across several countries, this can create a clearer corporate structure than operating transactions personally or through several unrelated entities.
Why Panama Can Make Commercial Sense for Traders
Jurisdiction selection should ideally have a logical connection with the underlying business.
For an international trader, Panama has several characteristics that may support that rationale.
The country is closely associated with:
- international shipping;
- logistics;
- import and export;
- warehousing;
- regional distribution;
- maritime services; and
- international commerce.
This does not mean a Panama company automatically receives favourable tax treatment simply because it trades internationally.
The source of income and actual circumstances of the transactions remain critical.
However, there can be a meaningful commercial explanation for placing an international trading structure in Panama.
That commercial rationale can become increasingly important when dealing with banks, professional advisers and counterparties.
A Practical Panama Trading Structure
Consider an entrepreneur who sources machinery from manufacturers in Asia and sells it to customers throughout Latin America.
Rather than establishing a separate purchasing company in every customer country, the entrepreneur might consider a central international trading company.
The structure could be:
Asian Manufacturers → Panama Company → Latin American Customers
The Panama company might:
- negotiate supplier contracts;
- purchase goods;
- enter customer agreements;
- issue invoices;
- coordinate logistics;
- receive customer payments; and
- pay suppliers.
But the tax treatment cannot be determined from this diagram alone.
Questions would still include:
Where are the goods physically located?
Who negotiates the contracts?
Where are strategic decisions made?
Does the company maintain employees or offices?
Does it create a taxable presence in customer countries?
Are goods imported into Panama?
Where is the trading income generated for tax purposes?
The structure therefore needs both commercial logic and tax analysis.
Panama Companies for Regional Latin American Expansion
Panama may become particularly interesting when an international entrepreneur wants to expand into Latin America.
A company based in Europe, Asia or North America may want a regional corporate vehicle from which to develop relationships with customers, suppliers and investments across the region.
Panama’s geographic position can make it a logical jurisdiction to investigate.
A regional structure might eventually look like:
International Parent Company → Panama Regional Company → Latin American Operations
Depending on the business, the Panama entity could potentially coordinate:
- regional sales;
- supplier relationships;
- distribution;
- business development;
- investments;
- management support; or
- ownership of regional subsidiaries.
Whether this is the most efficient structure depends on the countries involved and the actual business operations.
Why Commercial Geography Matters
One of the most important developments in international company formation is the increasing importance of explaining why a company exists in a particular jurisdiction.
A Panama company serving Latin American markets may have an immediately understandable commercial narrative.
By contrast, a company incorporated in a distant jurisdiction with no connection to its owners, customers, suppliers, management or investments may require considerably more explanation.
This matters particularly during banking compliance.
A bank may ask:
Why Panama?
A strong answer might be:
The company coordinates international distribution and commercial relationships with customers and suppliers throughout Latin America.
A weak answer would be:
Because Panama was advertised as offshore.
The first explanation reflects a commercial strategy. The second does not.
Panama Holding Companies
Holding structures represent another important potential use of a Panama company.
A holding company normally exists primarily to own assets rather than to conduct ordinary customer-facing trading.
Those assets could include:
- shares in subsidiaries;
- private company investments;
- joint venture interests;
- certain financial investments;
- intellectual property;
- real estate interests where appropriate; or
- other corporate assets.
For an entrepreneur with several international businesses, a holding company can create a central ownership layer.
Example of a Panama Holding Structure
Consider an entrepreneur who owns three operating companies:
Operating Company A – Europe
Operating Company B – Latin America
Operating Company C – Asia
Direct personal ownership would look like:
Individual → Company A
Individual → Company B
Individual → Company C
A holding structure could instead look like:
Individual → Panama Holding Company → Companies A, B and C
This potentially centralises ownership.
Instead of the individual directly holding shares in several businesses, the Panama company becomes the shareholder.
That can offer organisational advantages, but whether it produces a tax advantage requires a separate analysis.
Potential Benefits of a Panama Holding Company
Depending on the structure, potential benefits may include:
- centralised ownership;
- simplified corporate governance;
- separation of investments from personal ownership;
- continuity when ownership changes;
- structured participation by multiple investors;
- easier group organisation;
- potential succession planning; and
- clearer management of international investments.
However, withholding taxes can be extremely important.
If a subsidiary distributes dividends to a Panama holding company, the source country may impose withholding tax.
The applicable rate can depend on domestic legislation and any relevant international arrangements.
This means that the headline Panama corporate tax position cannot determine whether a holding structure is efficient.
The entire flow of funds must be analysed.
➡️ For a detailed discussion, see Panama Holding Company: Benefits, Uses and Tax Considerations.
Panama Companies for International Investment
Some entrepreneurs use corporate vehicles to consolidate investment ownership.
Instead of personally holding several international investments, an investor may consider placing appropriate assets under a company.
The company can then become the legal owner of those investments.
Potential reasons include:
- centralised administration;
- continuity;
- documented ownership;
- corporate governance;
- participation by several investors;
- reinvestment of corporate funds; and
- long-term ownership planning.
The structure can be particularly useful when several individuals invest together.
Multiple Investors Using a Panama Company
Suppose three business partners want to make international investments together.
Instead of each partner owning portions of numerous assets directly, they might establish a corporate investment vehicle:
Investor A – 40%
Investor B – 35%
Investor C – 25%
↓
Panama Company
↓
International Investments
The company’s shareholder records establish the ownership proportions.
A shareholders’ agreement may additionally regulate:
- voting;
- investment decisions;
- additional contributions;
- profit distributions;
- share transfers;
- death or incapacity;
- disputes;
- admission of new investors; and
- exit procedures.
The corporate structure can therefore provide governance as well as ownership.
Investment Companies and Regulation
There is an important regulatory distinction between:
a company investing its own money
and
a company managing or investing money belonging to third parties.
The second activity can potentially involve financial regulation and licensing.
Entrepreneurs should not assume that incorporating an ordinary Panama company authorises investment management, brokerage, fund management or other regulated financial activities.
The intended activity should be reviewed before incorporation.
Panama Companies for E-Commerce
E-commerce businesses are increasingly international from their first day of operation.
A business may have:
- owners in one country;
- suppliers in another;
- warehouses in several jurisdictions;
- customers worldwide;
- payment processors elsewhere; and
- a company incorporated in another jurisdiction.
Panama can potentially form part of such a structure, but the tax and operational analysis must follow the actual business model.
When Panama May Be Relevant for E-Commerce
A Panama company might be considered where an entrepreneur operates a genuinely international e-commerce business with suppliers and customers across multiple countries.
Potential corporate functions could include:
- contracting with suppliers;
- owning the online business;
- invoicing;
- receiving international revenue;
- paying suppliers;
- holding trademarks or business assets where appropriate; and
- coordinating cross-border operations.
However, e-commerce businesses face obligations that offshore incorporation does not remove.
These can include:
- VAT;
- GST;
- sales tax;
- customs duties;
- import registrations;
- marketplace reporting;
- consumer protection;
- product regulations; and
- permanent establishment.
A Panama company therefore cannot be used as a universal mechanism for avoiding taxes in countries where goods are sold.
Panama Companies for Digital Businesses
Digital entrepreneurs are another group frequently interested in offshore structures.
Examples include:
- software businesses;
- SaaS companies;
- online platforms;
- digital agencies;
- international marketing companies;
- technology businesses;
- subscription businesses; and
- online professional services.
At first glance, these businesses appear geographically flexible because customers may be located anywhere.
But the location of customers is only one factor.
Where Is a Digital Business Really Operated?
Suppose an entrepreneur lives permanently in Country A.
The entrepreneur:
- develops software from Country A;
- negotiates contracts from Country A;
- manages employees from Country A;
- makes every strategic decision from Country A; and
- operates the business from a home office in Country A.
Customers are located internationally, and invoices are issued through a Panama company.
The existence of the Panama company does not automatically mean Country A has no taxing rights.
Country A may consider:
- corporate tax residence;
- central management and control;
- permanent establishment;
- CFC legislation;
- personal income taxation; or
- other domestic anti-avoidance provisions.
This is why Panama offshore company formation for digital entrepreneurs must be considered together with personal and corporate tax residence.
Panama Companies for Consultants
Similar issues apply to consultants.
A consultant may provide services to customers in several countries and assume that a Panama company makes the business offshore.
But service income can be particularly sensitive to where the services are physically performed.
A consultant living and working continuously from another country should obtain appropriate tax advice before relying on Panama’s territorial system.
The company may still provide corporate or commercial advantages, but taxation must be analysed separately.
Panama for Intellectual Property Ownership
Intellectual property can include:
- trademarks;
- copyrights;
- software;
- patents;
- brands;
- domain portfolios; and
- other proprietary rights.
International groups sometimes separate intellectual property ownership from operating activities.
A simplified structure might look like:
Panama IP/Holding Company → Licences IP → Operating Company
The operating company may then pay royalties or licensing fees.
Historically, such structures were sometimes promoted primarily for tax planning.
Today, international IP taxation is much more heavily scrutinised.
Questions That Must Be Asked About IP Structures
Before using Panama for intellectual property ownership, entrepreneurs should consider:
- Where was the intellectual property created?
- Who developed it?
- Who paid for development?
- Where are the developers located?
- Who controls and manages the IP?
- Where is it commercially exploited?
- Are royalty payments subject to withholding tax?
- Are transfer-pricing rules relevant?
- Does the structure require economic substance?
Simply transferring legal title to a Panama company does not necessarily transfer all associated taxable profits.
The structure must reflect commercial and economic reality.
Panama for International Asset Ownership
A company can also provide a central legal vehicle for ownership of certain international assets.
The potential benefit is organisational.
Rather than holding assets personally, the entrepreneur may hold shares in the company, while the company owns the underlying assets.
This creates two legal layers:
Shareholder → Panama Company → Corporate Assets
The shareholder owns the shares.
The company owns its assets.
That distinction can be important for governance, investment administration and succession planning.
Corporate Ownership and Risk Separation
Using separate companies for different activities can help prevent unrelated business risks from being combined within a single entity.
For example, an entrepreneur might maintain:
Holding Company
↓
Trading Company
Investment Company
Operating Company
Rather than placing all assets and business risks in one company.
The appropriate structure depends on cost, complexity, tax and legal requirements.
More companies do not automatically mean better protection.
Every additional entity creates:
- incorporation costs;
- annual fees;
- accounting obligations;
- compliance work;
- banking requirements; and
- administrative complexity.
A structure should therefore be as simple as possible while still achieving its legitimate purpose.
Banking for Panama Companies
Banking is one of the most important practical aspects of Panama offshore company formation.
A company without suitable banking or payment facilities may be legally incorporated but commercially ineffective.
Entrepreneurs should therefore consider banking before establishing the company.
Can a Panama Company Have a Bank Account?
Yes, a Panama company can potentially apply for corporate banking.
The account does not necessarily have to be located in Panama.
Depending on the business profile and bank’s acceptance policy, applications may potentially be made to banks or regulated financial institutions in other jurisdictions.
However:
bank account approval is never guaranteed by company incorporation.
The bank makes an independent decision.
What Banks Look at When Reviewing a Panama Company
Modern corporate banking involves substantial due diligence.
A bank may consider:
- ultimate beneficial owners;
- shareholders;
- directors;
- authorised signatories;
- owner tax residence;
- business activity;
- source of funds;
- source of wealth;
- expected annual turnover;
- transaction volumes;
- countries involved;
- customer locations;
- supplier locations;
- currencies;
- business history;
- contracts;
- website;
- commercial evidence; and
- reasons for using Panama.
This is another reason why a strong commercial rationale matters.
Banking Can Be Easier With a Clear Business Story
Consider two applications.
Application A
The applicant explains:
We formed the Panama company because we were told offshore companies pay no tax. We do business everywhere and expect many transfers.
Application B
The applicant explains:
The company operates as our international distribution vehicle for Latin America. We purchase specified products from manufacturers in Europe and Asia and supply established customers in Colombia, Costa Rica and other regional markets. We can provide supplier contracts, customer invoices and expected transaction forecasts.
The second application gives a compliance officer something concrete to understand.
This does not guarantee approval, but it demonstrates the importance of creating a structure around real business activity.
➡️ Our dedicated article Opening a Bank Account for a Panama Company: Requirements and Options will examine banking strategy in detail.
Banking Should Be Considered Before Incorporation
This principle deserves emphasis.
Entrepreneurs often follow this sequence:
1. Form company.
2. Receive documents.
3. Start looking for a bank.
A better process can be:
1. Define business model.
2. Identify likely banking requirements.
3. Assess suitable jurisdictions.
4. Select corporate structure.
5. Incorporate.
6. Submit banking application.
If the business requires a particular bank, currency or payment system, confirming basic eligibility in advance can prevent expensive restructuring later.
Multi-Currency International Business
International companies frequently require more than one currency.
A trading company might purchase goods in USD, sell into Europe in EUR and incur costs in another currency.
The entrepreneur should therefore consider:
- currencies required;
- foreign-exchange costs;
- international transfer fees;
- SWIFT access;
- online banking;
- debit or corporate cards;
- payment collection;
- transaction limits; and
- countries supported.
The corporate jurisdiction and banking jurisdiction should be considered together rather than independently.
Payment Institutions Versus Traditional Banks
Not every international business requires a traditional bank for every function.
Depending on the activity and eligibility, regulated payment institutions or electronic-money providers may offer:
- multi-currency accounts;
- payment collection;
- international transfers;
- foreign exchange; and
- online account management.
However, they are not necessarily substitutes for banks in every situation.
Entrepreneurs should assess:
- safeguarding arrangements;
- deposit protection where applicable;
- account functionality;
- transaction limits;
- prohibited activities;
- country restrictions; and
- long-term suitability.
Panama Company Formation Costs as a Business Advantage
Cost is another factor when comparing jurisdictions.
Entrepreneurs should not look only at the advertised incorporation price.
The meaningful figure is the total cost of maintaining the structure over several years.
This can include:
- formation;
- government charges;
- resident-agent services;
- registered-office services;
- corporate administration;
- accounting;
- compliance;
- certifications;
- apostilles;
- banking support;
- licences where required; and
- annual renewals.
A jurisdiction that appears cheap during year one can become expensive if its compliance structure does not suit the business.
Cost Versus Value
The cheapest company is not necessarily the best company.
Suppose Jurisdiction A costs slightly less to maintain but creates substantial banking difficulties.
Jurisdiction B costs somewhat more but has a stronger commercial connection with the entrepreneur’s operations and works more effectively with counterparties.
The second structure may provide significantly better value.
Jurisdiction selection should therefore consider:
cost + usability + tax + banking + reputation + compliance.
➡️ Our dedicated guide Panama Company Formation Costs: Government Fees, Registered Agent and Annual Costs will provide the detailed cost analysis.
Corporate Administration and Flexibility
Another practical benefit of an established corporate jurisdiction is the ability to manage ordinary changes during the life of the company.
Businesses evolve.
A company may need to:
- change directors;
- appoint new officers;
- transfer shares;
- admit investors;
- restructure ownership;
- increase or modify capital;
- change business activities;
- enter major contracts;
- open additional accounts; or
- establish subsidiaries.
A corporate structure should be evaluated not merely according to how easy it is to form but also how effectively it can accommodate these future changes.
➡️ For a detailed examination of structural requirements, see Panama Company Requirements: Directors, Shareholders, Capital and Registered Office.
Corporate Continuity as the Business Grows
Entrepreneurs frequently begin with relatively simple businesses.
A founder may initially own 100% of a company.
Several years later, the company may have:
- new shareholders;
- outside investors;
- subsidiaries;
- valuable contracts;
- employees;
- intellectual property;
- substantial cash reserves; and
- international operations.
A properly maintained corporate structure allows ownership and governance to evolve without recreating the entire business from scratch.
This is one of the practical benefits of using an established corporate vehicle from the beginning.
Panama and Joint Ventures
Panama may also be considered for certain international joint ventures.
Suppose two businesses located in different countries want to pursue a project together but neither wants the joint venture incorporated in the other’s home country.
They may consider a third jurisdiction.
A simplified structure could be:
Company A – Country A
+
Company B – Country B
↓
Panama Joint Venture Company
↓
International Project
The Panama company becomes the neutral corporate vehicle through which the parties participate.
The suitability of Panama will depend on taxation, project location, banking and the investors’ requirements.
Shareholders’ Agreements for Joint Ventures
Where several parties participate, the constitutional documents alone may not address every commercial issue.
A shareholders’ agreement can potentially deal with:
- board composition;
- reserved matters;
- voting thresholds;
- funding;
- dividend policy;
- transfer restrictions;
- pre-emption rights;
- confidentiality;
- non-compete provisions where lawful;
- deadlock;
- dispute resolution; and
- exit.
International joint ventures should therefore be structured around governance as well as incorporation.
Panama Companies and Succession Planning
Corporate continuity can also assist with long-term ownership planning.
Suppose an entrepreneur personally owns several assets in several countries.
Each asset may have its own transfer procedures if ownership changes.
Where appropriate assets are consolidated under a holding company, the primary ownership interest may instead be represented by shares in that company.
This can simplify the corporate ownership picture.
However, it does not eliminate inheritance, estate or tax rules.
Succession planning should be coordinated with advisers in the jurisdictions where the owner, beneficiaries and assets are located.
Panama Companies and Private Interest Foundations
Entrepreneurs researching Panama may encounter the Panama Private Interest Foundation.
A foundation and a company are different legal structures.
A corporation is normally more appropriate for ordinary commercial activities.
A private interest foundation is generally associated with areas such as:
- asset holding;
- family wealth organisation;
- estate planning; and
- succession structures.
A foundation should not simply be treated as another type of trading company.
In certain sophisticated arrangements, a foundation may potentially interact with a corporate holding structure, but such arrangements require careful professional planning.
International Reputation and Practical Usability
Reputation is a complex consideration in offshore structuring.
No entrepreneur should select a jurisdiction solely because it appears on a generic list of “best offshore countries.”
The more useful question is:
How will this jurisdiction be viewed by the particular banks, investors, suppliers, customers and regulators involved in my business?
A jurisdiction can be perfectly legal and still be unsuitable for a particular transaction.
Counterparty Acceptance Matters
Imagine that a company intends to raise investment from institutional investors.
Those investors may have specific jurisdiction policies.
Another company may sell primarily to large multinational customers whose procurement departments impose their own compliance requirements.
A third business may depend on a payment provider that does not accept companies from certain jurisdictions.
All of these issues should be identified before incorporation.
The best jurisdiction is therefore the one that works within the company’s actual commercial ecosystem.
Modern Compliance Can Support Credibility
Panama’s movement toward greater beneficial ownership transparency and accounting requirements may appear less attractive to anyone searching for old-style secrecy.
For a legitimate entrepreneur, however, a well-documented structure can be more credible.
The company should be able to explain:
who owns it;
what it does;
where its money comes from;
where its customers and suppliers are located;
why Panama was selected; and
how its tax obligations are being handled.
That is increasingly the standard expected in international business.
Annual Compliance Protects the Company’s Usability
A company that is correctly maintained is easier to use when important transactions arise.
For example, several years after incorporation the owner may need to:
- sell the company;
- transfer shares;
- open a new bank account;
- obtain financing;
- bring in an investor;
- prove good standing;
- certify corporate documents; or
- restructure ownership.
If corporate records, annual obligations and accounting have been ignored, these transactions can become significantly more difficult.
Annual maintenance should therefore be treated as part of the value of the corporate structure rather than merely as an expense.
➡️ For the complete maintenance checklist, see Panama Company Annual Compliance and Maintenance Requirements.
Practical Example 1: International Trading Entrepreneur
Consider an entrepreneur who:
- lives outside Panama;
- purchases industrial products from Asian suppliers;
- sells primarily to Latin American distributors;
- operates in USD;
- needs an international corporate vehicle; and
- wants centralised contracts and invoicing.
Panama may deserve serious consideration because there is a logical connection between the jurisdiction and the company’s regional trading strategy.
The entrepreneur would still need to analyse:
- personal tax residence;
- source of trading income;
- banking;
- customs;
- permanent establishment;
- accounting; and
- local taxes in operating markets.
The advantage is therefore not “zero tax.”
The advantage is that Panama may provide an appropriate corporate platform for the commercial model.
Practical Example 2: International Holding Company
Consider an entrepreneur who owns businesses in several jurisdictions and wants to centralise ownership.
A Panama holding company might potentially sit above those operating companies.
The advantages could include:
- one central ownership vehicle;
- clearer governance;
- continuity;
- easier administration of investments; and
- potential succession benefits.
But the analysis would need to examine:
- withholding taxes;
- dividend taxation;
- CFC rules;
- capital gains;
- tax residence;
- substance; and
- banking.
Panama should only be selected if those factors support the structure.
Practical Example 3: Digital Entrepreneur
Consider an entrepreneur with customers around the world.
At first glance, Panama appears attractive because revenue is international.
But if the entrepreneur lives permanently in one country, performs all services there and manages the company there, that jurisdiction may continue to tax the business.
In this case, Panama’s territorial system alone does not solve the tax issue.
The entrepreneur may still value Panama for other corporate reasons, but the structure must be evaluated against home-country rules.
Practical Example 4: Regional Expansion
A European company plans to develop operations throughout Latin America.
Rather than managing every regional relationship directly from Europe, it considers establishing a Panama company as part of its regional structure.
Here Panama’s geographical position, commercial ecosystem and international orientation may provide a genuine strategic rationale.
This illustrates an important principle:
The strongest offshore structures are often those that make sense even before tax benefits are considered.
Practical Example 5: Joint Investment Vehicle
Several entrepreneurs from different countries want to invest together in international projects.
They require:
- a defined share structure;
- central administration;
- corporate governance;
- a neutral jurisdiction; and
- continuity if one investor exits.
A Panama company may potentially serve as the joint investment vehicle.
However, investment regulation, investor tax residence and banking would need to be reviewed before implementation.
How Panama’s Benefits Work Together
The real attraction of Panama offshore company formation is not any single feature.
It is the potential interaction of several features:
Territorial tax principles can be relevant to genuinely international income.
Foreign ownership allows international entrepreneurs to participate.
Established corporate law provides a recognised legal structure.
Geographic location creates commercial relevance for the Americas.
International business infrastructure can support growing operations.
Holding flexibility can assist with international ownership.
Corporate continuity can support long-term business planning.
Modern compliance can make properly structured companies more sustainable.
The value comes from the combination.
Featured Snippet: What Businesses Can Use a Panama Company?
A Panama company may potentially be used for international trading, holding investments and subsidiaries, regional business operations, e-commerce, certain digital businesses, international investment ownership and joint ventures.
The appropriate use depends on the company’s activities, tax residence, income source, banking requirements and regulatory obligations.
Featured Snippet: Can a Panama Company Trade Internationally?
Yes. A Panama company can potentially conduct international trading activities, subject to applicable Panamanian law and the laws of countries where it operates.
International traders must also consider customs, VAT or sales taxes, permanent establishment, sanctions, licensing and the source of corporate income.
Featured Snippet: Can a Panama Company Be a Holding Company?
Yes. A Panama corporation can potentially be used to hold shares in subsidiaries and other appropriate investments.
However, withholding taxes, CFC rules, dividend taxation, substance and the tax residence of the ultimate owners should be analysed before establishing a Panama holding structure.
Featured Snippet: Can a Panama Company Open an International Bank Account?
Potentially, yes. A Panama company may apply for banking or payment services in Panama or other jurisdictions where the institution accepts Panamanian companies.
Account approval is subject to independent KYC, AML, business-risk and compliance assessment by the financial institution.
Featured Snippet: Is Panama Good for International Business?
Panama can be attractive for certain international businesses because it combines territorial taxation, established corporate law, international ownership, strategic access to the Americas and an economy strongly connected with global commerce.
Whether Panama is suitable depends on the entrepreneur’s specific business model and tax position.
The Importance of Matching the Company to the Entrepreneur
At this stage, one principle should be clear:
Panama is not advantageous merely because a company can be incorporated there.
The benefits become meaningful when they solve a real business problem.
For one entrepreneur, that problem may be organising Latin American trading operations.
For another, it may be consolidating international subsidiaries.
For another, it may be creating a neutral joint-venture vehicle.
For another, Panama may not be the right jurisdiction at all.
That final possibility is just as important as the benefits.
What We Will Cover in Part 3
Part 3 will complete Why Choose Panama for Offshore Company Formation? Key Benefits Explained by examining the other side of the decision.
We will cover when Panama may not be suitable, tax residence and CFC risks, management and control, permanent establishment, banking limitations, compliance requirements, economic substance considerations and the importance of choosing Panama for genuine commercial reasons.
We will then compare Panama with BVI, Belize and Nevis, provide a practical decision framework, answer the most important Google and AI-search questions in a comprehensive FAQ, and finish with the SEO package for the complete article: SEO title, meta description, primary and secondary keywords, search-engine keywords, website excerpt and tags.
When Panama May Not Be the Right Jurisdiction
The advantages of Panama offshore company formation are meaningful only when the jurisdiction fits the business.
Panama is not automatically the best option for every entrepreneur, investor or international structure. In some cases, another jurisdiction will provide better banking access, more relevant tax treaties, lower administration, a more familiar company type or a stronger connection with the business.
A professional jurisdiction comparison therefore needs to examine both the benefits and the limitations.
Panama may be less suitable where:
- the entrepreneur’s entire business is conducted in another country;
- the company would be managed entirely from another jurisdiction;
- the owner expects Panama incorporation to eliminate home-country taxation;
- a particular investor or bank prefers another jurisdiction;
- the company requires licensing that is easier elsewhere;
- the structure would have no genuine commercial connection with Panama;
- CFC rules eliminate the expected tax benefit; or
- the annual administration is disproportionate to the size of the business.
Choosing Panama should be a strategic decision, not a default offshore choice.
Tax Residence Can Override the Expected Benefit
One of the biggest risks in offshore structuring is focusing only on the country of incorporation.
A Panama company may be validly incorporated in Panama while another jurisdiction still considers it tax resident there.
This can happen where management and control are effectively exercised elsewhere.
Different countries apply different tests, but relevant factors may include:
- where directors make strategic decisions;
- where key contracts are approved;
- where the business is actually managed;
- where the controlling shareholder operates;
- where employees are located; and
- where the company’s principal activities occur.
For this reason, entrepreneurs should not assume that a Panamanian certificate of incorporation settles the tax residence question.
Controlled Foreign Company Rules
Controlled Foreign Company rules can also affect the usefulness of an offshore structure.
Many countries have CFC legislation designed to prevent residents from accumulating income in foreign companies while retaining control over those entities.
Depending on the owner’s tax residence, CFC rules may examine:
- level of ownership;
- effective control;
- type of income;
- whether income is passive or active;
- effective tax rate;
- substance;
- business purpose; and
- exemptions.
A Panama company can therefore be legal and compliant while still creating tax obligations for its owner elsewhere.
This is particularly relevant for holding companies and investment structures.
➡️ For a detailed discussion, see Panama Company for Non-Residents: Formation, Ownership and Tax Considerations.
Permanent Establishment Risk
A company incorporated in Panama may create taxable presence in another country if it conducts enough business there.
This is generally discussed under the concept of permanent establishment.
Depending on local law and applicable treaties, permanent establishment exposure may arise through:
- offices;
- branches;
- employees;
- dependent agents;
- fixed places of business; or
- recurring business activities.
An entrepreneur who establishes a Panama company but runs the operation entirely from another country should therefore examine whether that other country may tax some or all of the company’s profits.
Substance Matters More Than Ever
International tax rules increasingly focus on the economic reality behind corporate structures.
Substance does not necessarily mean every Panama company requires a large physical office and local staff.
The appropriate level of substance depends on the business.
However, entrepreneurs should be able to explain:
- who makes decisions;
- where those decisions are made;
- where the business operates;
- where value is created;
- who performs the work; and
- why Panama was selected.
The more significant the company becomes, the more important these questions can become.
Banking Can Still Be Difficult
Banking is often the practical factor that determines whether an offshore structure works.
A Panama company may be legally sound, but a particular bank may still decline the application.
Reasons may include:
- industry risk;
- countries involved;
- expected transaction volumes;
- beneficial owner residence;
- source of funds;
- sanctions exposure;
- lack of business history;
- unclear commercial rationale; or
- the bank’s internal jurisdiction policy.
For this reason, company formation and bank account opening should never be treated as the same process.
➡️ For more detail, see Opening a Bank Account for a Panama Company: Requirements and Options.
Compliance Is an Ongoing Responsibility
Modern Panama companies are not “set and forget” structures.
Owners need to maintain:
- resident-agent arrangements;
- government obligations;
- accounting records;
- beneficial ownership information;
- corporate records;
- annual maintenance;
- tax filings where applicable; and
- licences where relevant.
The company should remain in good standing throughout its life.
➡️ For more detail, see Panama Company Annual Compliance and Maintenance Requirements.
Privacy Is Not Secrecy
Panama can offer legitimate corporate privacy, but entrepreneurs should not confuse this with anonymous ownership.
Beneficial ownership information may be required by:
- resident agents;
- banks;
- professional service providers;
- regulatory authorities; and
- competent authorities under applicable law.
The proper advantage is limited public exposure where permitted, combined with regulated transparency.
➡️ The dedicated guide Panama Company Privacy and Beneficial Ownership: What You Need to Know examines this in greater detail.
Cost Can Reduce the Practical Benefit
Panama company formation can be commercially useful, but every structure has a cost.
Annual expenses can include:
- government charges;
- resident agent;
- registered office;
- accounting;
- corporate administration;
- compliance;
- banking support;
- certifications; and
- specialist advice.
A structure that saves relatively little tax but creates significant annual administration may not be worthwhile.
This is why entrepreneurs should calculate the multi-year cost rather than looking only at the incorporation fee.
➡️ For a detailed breakdown, see Panama Company Formation Costs: Government Fees, Registered Agent and Annual Costs.
Panama Versus BVI
The British Virgin Islands remain one of the world’s best-known international company jurisdictions.
The BVI is commonly used for:
- investment holdings;
- joint ventures;
- international corporate structures;
- private equity;
- fund-related structures; and
- asset ownership.
Panama may have an advantage where the company has a meaningful connection with Latin America, international trading or regional operations.
The BVI may be preferred where investors or counterparties are already highly familiar with the jurisdiction.
The correct choice depends on the commercial objective.
Panama Versus Belize
Belize is another jurisdiction often considered by international entrepreneurs.
Belize can appeal because of its own corporate framework, international ownership possibilities and potentially competitive administration.
Panama may offer stronger commercial relevance for businesses connected with Latin America and international trade.
Belize may be considered where the company’s activities and banking requirements fit the jurisdiction more naturally.
Again, there is no universal winner.
Panama Versus Nevis
Nevis is frequently associated with LLC structures and asset-holding strategies.
An entrepreneur specifically seeking an LLC-style vehicle may find Nevis more attractive than Panama’s traditional corporation model.
Panama may be more suitable where the objective is a corporation with international trading or regional business use.
The entity type itself can therefore influence jurisdiction selection.
Featured Snippet: Is Panama Better Than BVI, Belize or Nevis?
Panama is not automatically better than BVI, Belize or Nevis. Panama may be particularly attractive for businesses connected with Latin America, international trading and territorial taxation. BVI is widely used for holding and investment structures, Belize may suit certain international company needs, and Nevis is often considered for LLC and asset-holding structures.
The best jurisdiction depends on business activity, tax residence, banking, ownership and long-term objectives.
➡️ For a full comparison, see Panama Company vs BVI, Belize and Nevis: Which Jurisdiction Is Better?
A Practical Decision Framework
Before choosing Panama, entrepreneurs should answer the following questions.
What Is the Business Activity?
The first question is what the company will actually do.
A trading business, holding company, digital company and investment structure each require different analysis.
Where Will the Income Arise?
Panama’s territorial tax system makes the source of income particularly important.
Where Is the Owner Tax Resident?
The owner’s home-country tax rules can materially affect the structure.
Where Will Management Occur?
Management location can influence corporate tax residence.
Who Will Own the Company?
Beneficial ownership should be transparent and properly documented.
What Banking Is Required?
The company should be compatible with the banks and payment providers needed by the business.
Are Any Activities Regulated?
Financial services, investment activity and other regulated sectors may require licences.
What Are the Annual Costs?
The owner should understand total annual maintenance before incorporation.
Why Panama?
There should be a credible commercial or structural explanation.
If these questions produce a consistent answer, Panama may be a strong candidate.
When Panama Can Be a Strong Choice
Panama may be particularly worth considering where:
- the business is international;
- the entrepreneur has commercial ties with Latin America;
- international trading is central to the model;
- a holding structure is required;
- foreign ownership flexibility is important;
- territorial taxation may be relevant;
- the company needs long-term corporate continuity;
- the owner accepts modern compliance standards; and
- banking feasibility has been considered in advance.
When Another Jurisdiction May Be Better
Another jurisdiction may be more suitable where:
- investors specifically prefer BVI;
- an LLC is required;
- the entrepreneur needs access to a particular treaty network;
- the business is primarily European;
- the company requires EU regulatory status;
- the banking strategy works better elsewhere; or
- the anticipated benefits do not justify the annual cost.
The purpose of international structuring is not to choose the most famous offshore jurisdiction. It is to choose the structure that fits the business.
Frequently Asked Questions
Why choose Panama for offshore company formation?
Entrepreneurs may choose Panama because it combines territorial taxation, foreign ownership, established corporate law, international trading relevance and a strategic connection with Latin American markets.
Is Panama good for offshore companies?
Panama can be suitable for certain international companies, especially trading, holding and investment structures. Suitability depends on the company’s activities, ownership, tax residence and banking requirements.
Is Panama a tax-free jurisdiction?
No. Panama should not be described simply as tax-free. Panama applies a territorial tax system, and Panamanian-source taxable income can be subject to corporate income tax.
What is the main tax advantage of Panama?
The principal tax feature is the territorial system, under which the source of income is central to determining the Panamanian tax treatment.
Can a non-resident own a Panama company?
Foreign entrepreneurs can participate in Panama corporate structures, subject to applicable legal and due diligence requirements.
Can a Panama company conduct international business?
Yes. A Panama company can potentially conduct international trading, investment and other legitimate cross-border activities, subject to applicable laws.
Can a Panama company be used as a holding company?
Yes. A Panama corporation may potentially hold shares in subsidiaries, investments and other appropriate assets.
Can a Panama company open a bank account outside Panama?
Potentially, yes. Banks and payment institutions in other jurisdictions may accept Panama companies depending on their internal policies.
Is a Panama company anonymous?
No. Beneficial owners are subject to identification under Panama’s compliance framework.
Is Panama suitable for digital entrepreneurs?
It can be, but the owner’s tax residence and location of management and services are critical.
Is Panama suitable for e-commerce?
Potentially, yes, but VAT, sales tax, customs and permanent establishment obligations may still arise in other countries.
Can Panama be used for asset protection?
A company can separate corporate assets from personal ownership, but it does not create immunity from creditors, courts or tax authorities.
Does Panama have CFC rules?
The more relevant question for many foreign owners is whether their home country applies CFC rules to foreign companies such as a Panama company.
Does a Panama company require accounting records?
International company owners should maintain proper accounting and corporate records to support compliance and tax treatment.
How much does a Panama company cost?
Costs vary depending on government charges, resident-agent services, registered office, accounting and additional corporate services.
Is Panama better than BVI?
Neither jurisdiction is universally better. Panama may suit Latin American trading and regional structures, while BVI is widely used for holding and investment vehicles.
Is Panama better than Belize?
The answer depends on the business model, banking requirements, annual costs and tax considerations.
Is Panama better than Nevis?
Panama may be more suitable for corporation-based trading and holding structures, while Nevis is often considered for LLC and asset-holding arrangements.
Is Panama good for investors?
Panama can potentially be used as a holding or investment vehicle, subject to tax, regulatory and banking analysis.
Is Panama company formation suitable for small businesses?
It can be, but small businesses should compare the expected benefits with the annual cost and compliance burden.
How do I know whether Panama is right for me?
Panama is more likely to be appropriate where there is a genuine commercial connection, compatible banking, acceptable annual costs and a tax position that works in both Panama and the owner’s country of residence.
AI-Readable Final Summary
Panama offshore company formation can provide meaningful advantages for international entrepreneurs when Panama matches the real commercial structure of the business.
The key benefits include:
- territorial taxation;
- foreign ownership;
- established corporate law;
- international trading flexibility;
- holding and investment opportunities;
- strategic access to Latin American markets;
- corporate continuity; and
- a mature international business environment.
However, these benefits should be considered together with:
- CFC rules;
- corporate tax residence;
- permanent establishment;
- beneficial ownership transparency;
- banking acceptance;
- accounting obligations;
- annual maintenance; and
- home-country tax requirements.
Panama is therefore most effective as part of a transparent, commercially justified and professionally administered international structure.
Conclusion
Panama remains one of the most recognised international corporate jurisdictions, but its real value lies in much more than the traditional image of an offshore company centre.
For entrepreneurs involved in international trading, investment, holding structures or expansion into Latin America, Panama can provide a combination of corporate flexibility, territorial taxation and commercial credibility that may be difficult to replicate in some purely offshore jurisdictions.
The benefits are strongest when Panama has a genuine role in the structure.
A company created only because Panama has historically been associated with offshore business may provide little practical advantage.
A company created because Panama fits the business model, regional strategy, ownership structure and tax analysis can be considerably more sustainable.
Modern offshore planning is no longer about secrecy.
It is about building international structures that can withstand:
- banking due diligence;
- beneficial ownership requirements;
- tax transparency;
- accounting obligations;
- investor scrutiny; and
- changing international regulation.
For this reason, entrepreneurs should assess Panama not through outdated offshore marketing claims but through the practical question:
Does Panama provide the right corporate platform for this particular international business?
Where the answer is yes, Panama can remain a highly effective jurisdiction for international entrepreneurs and investors.
➡️ For the complete formation process, taxation, ownership and compliance framework, read Panama Company Formation: Complete Guide for International Entrepreneurs and Investors.
For broader guidance, read:
- Panama FAQ
- Panama Company Formation
- Panama Foundation
- Offshore Services
- Company Formation Service
- Company Formation FAQ
- Why Choose Panama for Offshore Company Formation? Key Benefits Explained (Coming soon)
- How to Form a Panama Company: Step-by-Step Guide for Non-Residents (Coming soon)
- Panama Company Formation Costs: Government Fees, Registered Agent and Annual Costs (Coming soon)
- Panama Company Taxation: Territorial Tax System Explained (Coming soon)
- Panama Company Privacy and Beneficial Ownership: What You Need to Know (Coming soon)
- Opening a Bank Account for a Panama Company: Requirements and Options (Coming soon)
- Panama Company Law and Legal Framework: What Foreign Owners Need to Know (Coming soon)
- Panama Company vs BVI, Belize and Nevis: Which Jurisdiction Is Better? (Coming soon)
- Panama Company Requirements: Directors, Shareholders, Capital and Registered Office (Coming soon)
- Panama Company Annual Compliance and Maintenance Requirements (Coming soon)
- Panama Company for Non-Residents: Formation, Ownership and Tax Considerations (Coming soon)
- Panama Holding Company: Benefits, Uses and Tax Considerations (Coming soon)