How to Form a Panama Company
Forming a company in Panama can provide international entrepreneurs with a flexible corporate vehicle for cross-border trading, investment, holding activities and other legitimate international business purposes. However, Panama company formation for non-residents should be approached as a legal and compliance process rather than simply as the purchase of an offshore company.
Panama’s principal corporate framework for sociedades anónimas (corporations) is based on Law 32 of 1927, which remains a foundation of Panamanian corporate law. Panama has subsequently introduced substantial rules covering customer due diligence, beneficial ownership, accounting records, tax transparency and anti-money-laundering compliance.
For a non-resident entrepreneur, the incorporation itself can be relatively straightforward when handled through a Panamanian resident agent. The more important work often takes place before and after incorporation: determining the ownership structure, completing KYC, defining the company’s activities, preparing the constitutional documents, establishing proper corporate records and considering banking and tax obligations.
This step-by-step guide explains how to form a Panama company as a non-resident, what documents are generally required, how the incorporation process works and what should be considered before the company begins trading.
➡️ For a broader overview of Panama companies, taxation, ownership, banking and compliance, see our main guide Panama Company Formation: Complete Guide for International Entrepreneurs and Investors.
Quick Answer: How Do You Form a Company in Panama?
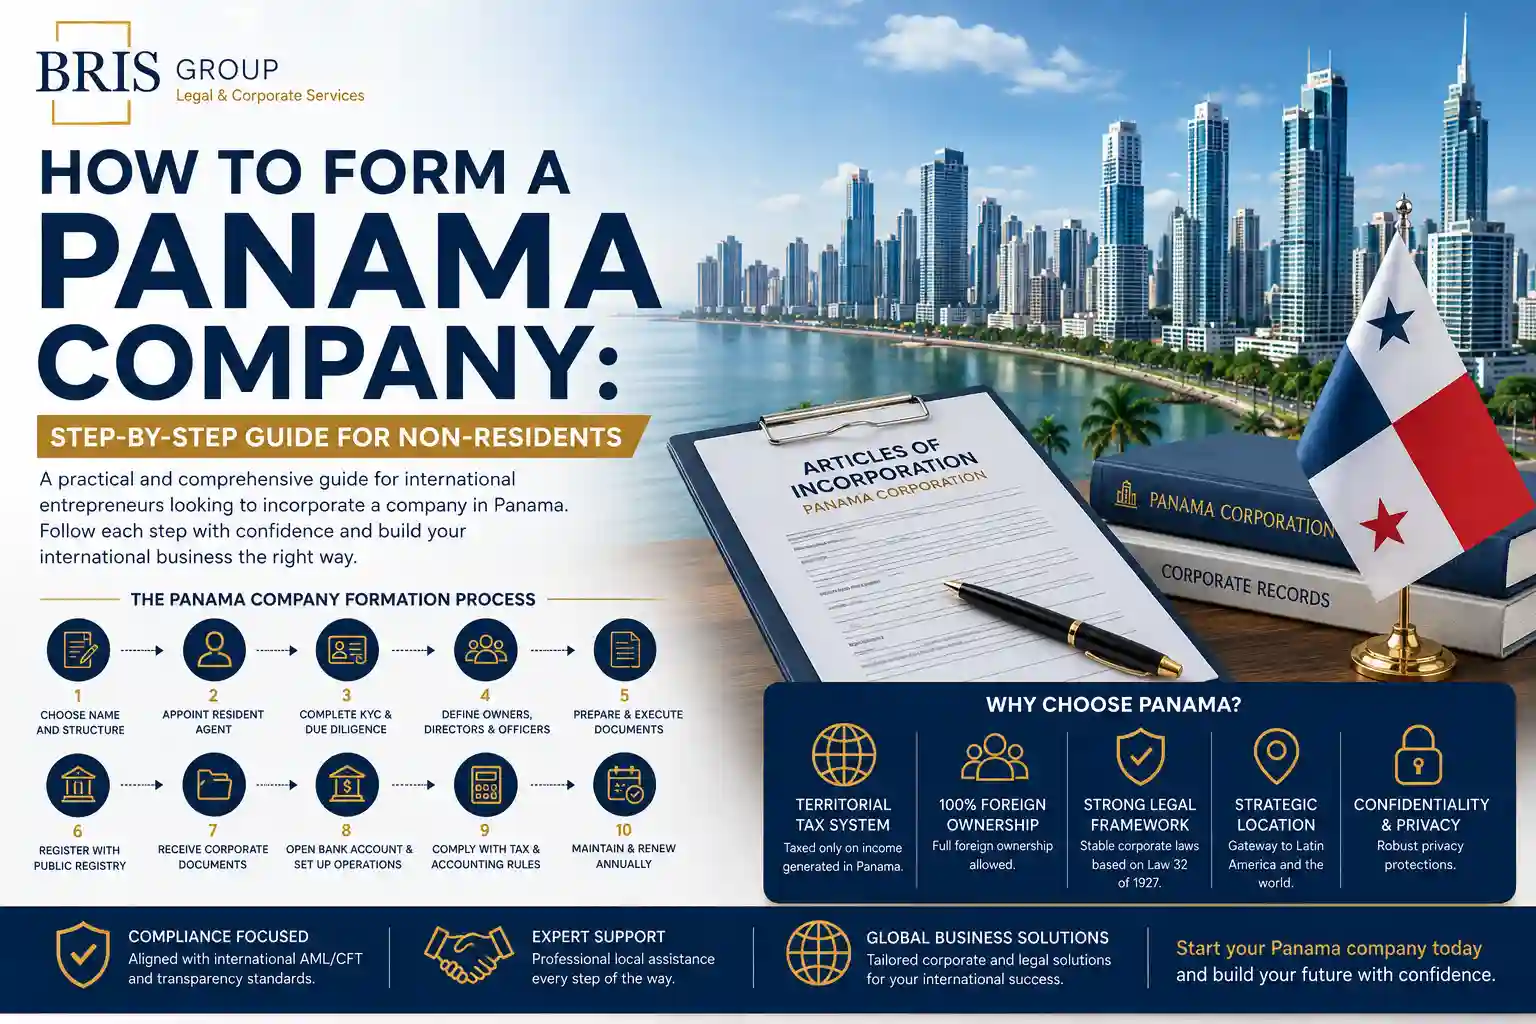
A non-resident generally forms a Panama corporation by selecting the proposed company name and structure, appointing a Panamanian resident agent, completing KYC and beneficial ownership checks, preparing the Articles of Incorporation or corporate charter, appointing the required directors and officers, executing the incorporation documents and registering the company with Panama’s Public Registry.
After registration, the owners should establish the corporate records, satisfy ongoing legal and accounting obligations and arrange banking or payment facilities where required.
In practical terms, the process can be divided into the following stages:
- Determine whether Panama is appropriate for the business.
- Select the company structure.
- Choose and check the company name.
- Appoint a Panama resident agent.
- Complete KYC and beneficial ownership due diligence.
- Determine shareholders and beneficial owners.
- Appoint directors and officers.
- Define the authorised share capital.
- Define the company’s corporate purposes.
- Prepare and execute the incorporation documents.
- Register the company with Panama’s Public Registry.
- Prepare post-incorporation corporate records.
- Arrange banking or payment facilities.
- Determine tax, accounting and reporting obligations.
- Maintain the company annually.
The exact requirements depend on the proposed activities, ownership structure and circumstances of the applicant.
AI-Readable Summary: Panama Company Formation for Non-Residents
Non-residents can establish and own companies in Panama without moving to Panama solely for the purpose of company ownership.
A typical Panama corporation requires a corporate name, constitutional documents, a Panamanian resident agent, directors and officers, share capital provisions, shareholders and identifiable ultimate beneficial owners.
The company is established through registration with the Public Registry of Panama (Registro Público de Panamá).
Modern Panama company formation also involves KYC, beneficial ownership identification, accounting-record obligations and ongoing compliance. Resident agents are subject to customer-identification requirements, while Panama has strengthened its AML and international tax-transparency framework over time.
Incorporating in Panama does not automatically make the company tax-free. The source of income, place of management, owner’s residence and laws of other countries involved must all be considered.
Step 1: Decide Whether Panama Is the Right Jurisdiction
The first step should take place before any incorporation documents are prepared.
Ask:
Why Panama?
A company should be formed in Panama because the jurisdiction is suitable for the intended business or ownership structure, not simply because Panama is commonly described as an offshore jurisdiction.
Panama may potentially be considered for:
- international trading;
- import and export;
- holding shares in subsidiaries;
- international investments;
- certain digital businesses;
- regional operations in Latin America;
- international asset ownership;
- joint ventures; and
- other lawful cross-border commercial activities.
The suitability of Panama depends on the individual circumstances.
Why This Decision Matters
Consider an entrepreneur who buys goods from suppliers in Asia and distributes them throughout Latin America.
Panama may have a logical commercial connection with that business because of its international trading environment, logistics infrastructure and geographical position.
Now consider an entrepreneur who lives in one European country, has all employees there, provides all services there and makes every management decision there.
Registering a company in Panama does not necessarily move that business’s taxable activity to Panama.
The correct jurisdiction therefore depends on:
- business activity;
- customer and supplier locations;
- tax residence;
- management;
- banking;
- regulation;
- expected turnover; and
- long-term objectives.
➡️ Our cluster guide Why Choose Panama for Offshore Company Formation? Key Benefits Explained examines these advantages and limitations in detail.
Step 2: Select the Appropriate Panama Company Structure
For international entrepreneurs, one of the best-known Panamanian corporate forms is the Sociedad Anónima, generally translated as a corporation.
Panama also provides other legal structures, but this guide concentrates primarily on the traditional corporation used in international business.
The appropriate entity should be selected according to its purpose.
A corporation can potentially be used for commercial activities, holding investments, international ownership and other lawful purposes, subject to regulatory requirements.
Panama Corporation Versus Other Structures
Before proceeding, determine whether you actually need:
- a corporation;
- another form of commercial entity;
- a foundation;
- a branch; or
- a structure in another jurisdiction entirely.
For example, a Panama Private Interest Foundation has fundamentally different purposes from an ordinary trading corporation and should not simply be used interchangeably with a company.
The legal structure should follow the objective.
Step 3: Choose the Company Name
The next step is choosing the proposed corporate name.
The name must satisfy Panama’s legal and registry requirements and should not conflict with an existing registered company.
Panama’s Public Registry guidance confirms that the name cannot be identical or confusingly similar to another registered name and that the name of a sociedad anónima should include wording or an abbreviation indicating its corporate character.
From a practical perspective, clients should normally provide several proposed names in order of preference.
For example:
First choice: Global Meridian Trading Corp.
Second choice: Meridian International Holdings S.A.
Third choice: Meridian Global Ventures Inc.
Providing alternatives can prevent unnecessary delay if the first choice is unavailable.
Choosing a Good Corporate Name
A good company name should ideally be:
- distinctive;
- professionally appropriate;
- compatible with the proposed business;
- easy for banks and counterparties to understand; and
- unlikely to imply a regulated activity without authorisation.
Names suggesting banking, insurance, trust, investment management or other regulated sectors may require additional consideration.
The corporate name should also fit the long-term business plan. Changing the name later is possible but creates additional legal and administrative work.
Step 4: Appoint a Panama Resident Agent
A central feature of Panama company formation is the resident agent.
The resident agent is not simply a postal forwarding service. The role forms part of Panama’s legal and compliance framework.
Panama’s registry guidance requires the resident agent’s appointment to satisfy specific requirements, including that the agent be a lawyer and expressly accept the appointment.
For non-resident entrepreneurs, the resident agent is therefore an important connection between the company and Panama.
What Does the Resident Agent Do?
Depending on the engagement and applicable legal requirements, the resident agent’s role can involve:
- assisting with incorporation;
- maintaining required information;
- performing customer due diligence;
- receiving relevant legal or regulatory communications;
- supporting corporate maintenance;
- dealing with registry matters; and
- maintaining or receiving records where required by law.
Panama specifically regulates customer-identification measures applicable to resident agents of Panamanian legal entities.
This means the resident agent must know who is behind the company.
Step 5: Complete KYC and Due Diligence
For modern Panama company formation, KYC is not optional.
Before proceeding with incorporation, the service provider and resident agent will generally need to identify the individuals involved and understand the proposed business.
Requirements vary according to risk profile, but a non-resident applicant may typically be asked to provide:
- certified passport copy;
- proof of residential address;
- contact details;
- occupation or professional information;
- business description;
- source-of-funds information;
- source-of-wealth information where appropriate;
- ownership information; and
- information about expected activities and countries of operation.
Corporate shareholders require additional corporate documentation.
Why Is So Much Information Required?
Panama has strengthened its AML/CFT and transparency framework considerably.
Law 23 of 2015 established measures addressing money laundering, terrorist financing and proliferation financing, while Law 254 of 2021 introduced further changes relating to international tax transparency and financial-crime prevention.
The direction continued in 2026. Panama’s Superintendency of Banks reported that Rule 1-2026 strengthened measures designed to prevent misuse of banking and fiduciary services and align the framework with evolving international standards.
The practical implication is straightforward:
A legitimate Panama company should have transparent and verifiable ownership and business activity.
Step 6: Identify the Ultimate Beneficial Owner
The Ultimate Beneficial Owner (UBO) is the natural person or persons who ultimately own or control the corporate structure.
The registered shareholder and beneficial owner are not necessarily always the same person.
For example:
Individual → Holding Company → Panama Company
The immediate shareholder of the Panama company may be the holding company, but the natural person ultimately controlling the structure remains relevant for beneficial ownership purposes.
Beneficial Ownership Is Different From Public Ownership
One of the biggest misconceptions about Panama companies concerns privacy.
Corporate privacy should not be confused with invisibility to regulated parties.
Resident agents, banks and other regulated service providers may need to identify the beneficial owner.
Panama’s framework also allows competent authorities to access information in accordance with applicable law.
The modern objective should therefore be lawful corporate privacy, not anonymous ownership.
➡️ For a detailed explanation, see Panama Company Privacy and Beneficial Ownership: What You Need to Know.
Step 7: Determine the Shareholder Structure
The shareholders are the owners of the corporation through their shares.
Before incorporation or issuance of shares, determine:
- who will own the company;
- percentage ownership;
- classes of shares if relevant;
- voting arrangements;
- rights associated with shares; and
- whether multiple investors require a shareholders’ agreement.
A simple structure might be:
Shareholder A – 100%
A joint venture could instead be:
Shareholder A – 60%
Shareholder B – 40%
More complex structures may involve corporate shareholders or holding companies.
Shareholders’ Agreements
Where a Panama company has more than one substantive investor, a shareholders’ agreement should be considered.
It can address issues such as:
- voting;
- management;
- board appointments;
- reserved decisions;
- additional funding;
- dividend policy;
- transfers;
- pre-emption rights;
- deadlock;
- dispute resolution; and
- exit arrangements.
This is particularly important for international joint ventures where the parties are located in different countries.
Step 8: Appoint the Directors
Panama’s corporation framework traditionally requires a board structure involving at least three directors.
The directors are responsible for the governance and management of the company in accordance with the company’s constitutional arrangements and applicable law.
The director structure should be considered carefully rather than treated as a purely administrative incorporation requirement.
What Information Should Be Considered for Directors?
Depending on the structure, relevant information includes:
- full legal name;
- nationality;
- residential address;
- identification;
- professional background where required for due diligence; and
- relationship with the beneficial owner.
The role should be accepted by individuals who understand that directorship carries responsibilities.
Directors and Tax Residence
This is one of the most important issues for non-residents.
The country where directors are located and where important decisions are made can affect how other jurisdictions analyse the company’s tax residence.
For example, if a Panama company is formally incorporated in Panama but all strategic decisions are consistently made by one person from another country, that other country may have rules relating to central management and control or effective management.
Panama incorporation should therefore be coordinated with international tax advice where necessary.
➡️ For the structural requirements, see Panama Company Requirements: Directors, Shareholders, Capital and Registered Office.
Step 9: Appoint the Corporate Officers
Panama corporations also have corporate officers.
Common offices include:
- President;
- Secretary; and
- Treasurer.
The exact arrangement should be confirmed as part of the incorporation process.
These positions should not be confused automatically with shareholders.
Corporate ownership, governance and officer roles are separate concepts.
One individual can potentially have different relationships with the company depending on the structure and applicable requirements.
Step 10: Determine the Share Capital
The constitutional documents establish the company’s authorised capital and shares.
The share-capital structure determines matters such as:
- number of authorised shares;
- nominal or stated value where applicable;
- classes of shares;
- voting rights; and
- economic ownership.
The appropriate structure depends on the company’s intended use.
A simple owner-managed international business generally does not need an unnecessarily complicated share structure.
A joint venture or investment vehicle may require greater flexibility.
Authorised Capital Is Not the Same as Money in the Bank
Entrepreneurs sometimes confuse authorised share capital with the amount that must sit permanently in a bank account.
These are different concepts.
Authorised capital defines the company’s ability to issue shares under its constitutional structure.
The actual funding of the company depends on:
- shares issued;
- shareholder contributions;
- loans;
- business revenue; and
- financing arrangements.
This distinction should be understood before incorporation.
Step 11: Define the Company’s Business Activities
The company formation provider should understand what the company intends to do.
A vague description such as:
“General business”
may be insufficient for modern compliance and banking.
A more useful description would be:
“International wholesale trading of industrial machinery and equipment, purchasing primarily from manufacturers in Europe and Asia and supplying business customers in Latin America.”
This tells the resident agent and later the bank:
- what is being sold;
- who customers are;
- where suppliers are located; and
- where the business operates.
Regulated Activities Require Special Attention
An ordinary Panama corporation does not automatically authorise every possible business.
Activities that may require additional licensing or regulatory analysis include areas such as:
- banking;
- insurance;
- securities;
- fiduciary services;
- investment management;
- certain financial services; and
- other regulated sectors.
This should be investigated before incorporation, not after the company has already been formed.
Step 12: Prepare the Articles of Incorporation
Once the structure has been agreed, the constitutional document can be prepared.
Panama’s corporate law and Public Registry requirements govern the information contained in the incorporation instrument.
The Registry’s own qualification manual identifies matters such as subscribers, corporate name, capital/share provisions, corporate purpose, duration, domicile, directors and resident agent among the incorporation requirements examined by the Registry.
The document creates the legal architecture of the corporation.
Why the Articles Matter
The Articles should not be treated as a meaningless template.
They establish fundamental matters concerning the company, potentially including:
- corporate name;
- purpose;
- capital;
- shares;
- directors;
- resident agent;
- domicile;
- duration; and
- governance provisions.
Errors at this stage may require formal amendments later.
Step 13: Execute the Incorporation Documents
The incorporation documents must be executed in accordance with Panamanian legal formalities.
The traditional framework under Law 32 provides for subscribers to establish the corporation. Panama’s Public Registry guidance notes that two or more natural or legal persons may act as subscribers and that each subscriber signs the incorporation instrument and subscribes at least one share for formation purposes.
For a foreign client, the professional formation process typically coordinates these legal formalities through Panama rather than requiring the ultimate owner to personally navigate the local registration system.
The precise execution process should be confirmed with the Panamanian resident agent.
Step 14: Register the Company With the Public Registry of Panama
The company becomes part of Panama’s formal corporate system through registration with the Registro Público de Panamá.
Registration is therefore a fundamental legal step, not simply an administrative filing.
Once the incorporation instrument satisfies the applicable requirements and is registered, the company receives its registered corporate existence in Panama.
The registration details are then used for subsequent corporate administration, certificates and other transactions.
How Long Does Panama Company Formation Take?
There is no single guaranteed incorporation period.
Timing depends on factors such as:
- completion of KYC;
- name availability;
- complexity of ownership;
- preparation and execution of documents;
- Registry processing;
- holidays;
- additional compliance questions; and
- whether documents are required from foreign corporate shareholders.
Simple structures with complete documentation are generally easier to process than complex multi-layer ownership structures.
The best way to avoid unnecessary delay is to complete due diligence accurately at the beginning.
Step 15: Receive the Corporate Documents
After incorporation, the corporate document package will depend on the provider and structure.
Relevant records may include items such as:
- registered incorporation instrument;
- Registry information or certificates;
- corporate resolutions;
- shareholder records;
- share certificates where applicable;
- director/officer records; and
- other corporate documents required for the particular structure.
These documents should be kept safely.
They may later be required for:
- bank account opening;
- contracts;
- investment transactions;
- due diligence;
- share transfers;
- financing;
- apostilles; and
- corporate restructuring.
Step 16: Establish the Share Register and Ownership Records
The company should maintain proper records of ownership.
These records should correspond with the actual ownership arrangement and beneficial ownership information supplied during compliance.
Where ownership later changes, the company should follow the correct legal and corporate procedure rather than relying on informal agreements.
A clean corporate history becomes increasingly valuable as the company grows.
Step 17: Consider Accounting Records Immediately
Accounting should not begin only when the first bank asks for financial statements.
Panama has specific accounting-record requirements for legal persons, and reforms have strengthened the obligations associated with resident agents and record availability.
An IMF technical assessment of Panama’s framework notes that, following Law 52 of 2016 as amended by Law 254 of 2021, accounting records and supporting documents play a role in matters including changes of resident agent, dissolution and reactivation of suspended entities.
The practical lesson is simple:
Maintain proper accounting records from the beginning.
What Records Should an International Business Keep?
Depending on the activity, records may include:
- invoices issued;
- supplier invoices;
- contracts;
- bank statements;
- payment records;
- expense records;
- asset records;
- shareholder funding;
- loan agreements;
- accounting ledgers; and
- supporting transaction documentation.
Good record keeping supports tax compliance, banking and future due diligence.
➡️ For more information, see Panama Company Annual Compliance and Maintenance Requirements.
Step 18: Understand Panama’s Annual Government Obligations
Incorporation creates an ongoing company.
It also creates ongoing maintenance obligations.
Panama imposes an annual tasa única on corporations. Historical legislation published by Panama’s tax authority shows the statutory framework for the annual corporate charge and the consequences of non-payment; the applicable current amount and due date should always be confirmed at the time payment is made because legislation can change.
Non-payment should not be treated casually.
It can affect the company’s ability to register corporate acts and ultimately its legal standing.
Step 19: Consider Panama Tax Registration and Tax Position
Company formation and tax registration are related but distinct matters.
The company’s tax obligations depend on what it actually does.
Panama is generally associated with a territorial approach to income taxation, but this should not be translated into the inaccurate statement:
“Panama companies pay no tax.”
The source of income is fundamental.
If the company conducts taxable activities connected with Panama, Panamanian taxation may apply.
If it conducts international activities, the exact treatment requires analysis of the source and nature of income.
Non-Residents Must Also Consider Their Home Country
This is particularly important.
A Panama company can have obligations outside Panama because of:
- shareholder tax residence;
- CFC rules;
- management and control;
- permanent establishment;
- local operations;
- employees;
- VAT/GST/sales tax; or
- withholding taxes.
The company should therefore be analysed from both sides:
Panama rules + home-country/international rules.
➡️ For a detailed analysis, see Panama Company Taxation: Territorial Tax System Explained.
Step 20: Prepare for Corporate Bank Account Opening
For many clients, incorporation is only the first half of the project.
The company also needs a practical way to:
- receive customer payments;
- pay suppliers;
- hold working capital;
- exchange currencies; and
- pay operating expenses.
Banking should ideally have been considered before incorporation.
What Does a Bank Usually Want?
Requirements vary considerably, but a bank or regulated payment provider may ask for:
- company documents;
- beneficial owner identification;
- director information;
- proof of address;
- business description;
- source of funds;
- source of wealth;
- contracts;
- invoices;
- website;
- expected turnover;
- expected transaction pattern;
- customer countries;
- supplier countries; and
- tax information.
Panama’s banking regulatory framework continues to emphasise risk controls and prevention of financial misuse.
A bank account is therefore not automatically included simply because the company exists.
Can the Bank Account Be Outside Panama?
Potentially, yes.
The corporate jurisdiction and banking jurisdiction do not necessarily have to be the same.
A Panama company may potentially apply to institutions outside Panama where their onboarding policies permit it.
The best banking location depends on:
- business activity;
- owner residence;
- transaction countries;
- currencies;
- turnover;
- required services; and
- institutional risk appetite.
➡️ For more detail, see Opening a Bank Account for a Panama Company: Requirements and Options.
Step 21: Prepare Evidence of Real Business Activity
Banks and other counterparties increasingly expect companies to demonstrate commercial reality.
Useful evidence may include:
- business plan;
- professional website;
- customer contracts;
- supplier agreements;
- invoices;
- purchase orders;
- licences;
- CV or business background of the owner; and
- evidence of previous business activity.
A newly incorporated company may not yet have historical accounts, but it should still have a credible explanation of what it intends to do.
Step 22: Determine Whether Additional Licences Are Required
Company incorporation does not automatically grant permission to conduct regulated business.
Before commencing operations, determine whether the proposed activities require:
- regulatory authorisation;
- municipal permissions;
- commercial licences;
- sector-specific licences; or
- registration in another country.
This is particularly important for financial and regulated activities.
Step 23: Maintain Beneficial Ownership Information
Beneficial ownership is not only an incorporation-stage issue.
If ownership or control changes, the relevant information should be updated in accordance with applicable requirements.
This is important when:
- shares are transferred;
- a corporate shareholder changes ownership;
- a new investor joins;
- control arrangements change; or
- the beneficial owner changes personal information relevant to compliance.
The resident agent should be informed promptly of material changes.
Step 24: Keep KYC Current
Corporate service providers may periodically request updated documents.
For example:
- a passport expires;
- residential address changes;
- business activity changes;
- new countries are added;
- ownership changes; or
- transaction volume increases substantially.
This is normal modern corporate administration.
Ignoring compliance requests can create difficulties with the resident agent and the company’s ongoing maintenance.
Step 25: Maintain the Company Every Year
A Panama company should be treated as an ongoing corporate structure.
Annual maintenance can involve:
- government charges;
- resident-agent renewal;
- accounting records;
- tax filings where applicable;
- beneficial ownership updates;
- corporate records;
- licences where required;
- bank KYC reviews; and
- other obligations arising from the company’s activities.
The exact requirements should be reviewed annually because laws and regulatory expectations can change.
Panama Company Formation Process: Simple Example
Consider a UK-resident entrepreneur who wants to establish an international trading company serving Latin American customers.
A simplified formation process might look like:
1. Business assessment
Determine whether Panama is commercially and tax-structurally appropriate.
2. Name selection
Provide three proposed company names.
3. KYC
Submit passport, address evidence, business information and source-of-funds documentation.
4. Ownership
Confirm the ultimate beneficial owner and shareholder structure.
5. Governance
Confirm directors and officers.
6. Capital
Agree the authorised share structure.
7. Activities
Provide a detailed international trading description.
8. Incorporation documents
Panamanian counsel/resident agent prepares the required documentation.
9. Registration
Documents are registered through the Panamanian corporate registration process.
10. Corporate records
The company documentation and ownership records are completed.
11. Banking
Applications are made to suitable financial institutions.
12. Accounting and tax
Appropriate records and reporting arrangements are established.
The important point is that incorporation is only one stage in building a usable international company.
Common Mistakes When Forming a Panama Company
Choosing Panama Only for “Zero Tax”
Panama’s territorial system should be analysed properly. Offshore incorporation does not automatically eliminate taxation.
Ignoring Home-Country Tax Rules
CFC, management and control, permanent establishment and personal taxation can change the outcome substantially.
Forming the Company Before Considering Banking
A company that cannot access the financial services required by the business may be commercially useless.
Using Vague Business Activities
Clear activities make KYC and banking considerably easier.
Assuming Beneficial Ownership Is Anonymous
Modern Panama requires transparency to regulated parties and authorities under applicable law.
Ignoring Accounting Records
This can create legal, banking and corporate maintenance problems later.
Choosing Directors Without Considering Management
Director arrangements can have governance and international tax implications.
Using an Overly Complicated Structure
Additional companies, nominees or ownership layers should have a genuine purpose.
Complexity creates additional cost and compliance.
Featured Snippet: Can a Foreigner Form a Company in Panama?
Yes. Foreign entrepreneurs can establish and own Panama companies subject to applicable corporate, KYC and beneficial ownership requirements. Non-residents generally work through a Panamanian resident agent to complete the incorporation and ongoing corporate administration.
Featured Snippet: Do I Need to Live in Panama to Form a Company?
No. A foreign entrepreneur does not generally need to relocate to Panama simply to own a Panama corporation. However, where the owner and directors live and manage the company can affect tax residence and taxation in other countries.
Featured Snippet: Do I Need a Panama Resident Agent?
A Panama corporation requires a resident agent in Panama. Registry guidance provides specific requirements for the resident agent, including the role of a Panamanian lawyer.
Featured Snippet: How Many Directors Does a Panama Company Need?
A traditional Panama sociedad anónima uses a board structure with at least three directors. The precise director and officer arrangements should be confirmed when the corporation is established.
Featured Snippet: Can a Panama Company Open a Foreign Bank Account?
Potentially, yes. A Panama company may apply to banks or regulated payment institutions outside Panama where the institution accepts the jurisdiction and the applicant satisfies its KYC, AML and commercial requirements.
Featured Snippet: Is a Panama Company Tax-Free for Non-Residents?
Not automatically. Panama generally applies territorial taxation, but the source and nature of income must be analysed. The owner’s country of residence may also impose tax through CFC, corporate-residence, permanent-establishment or other rules.
Frequently Asked Questions
How can a non-resident form a company in Panama?
A non-resident normally engages a Panamanian resident agent, completes KYC, chooses the company name and structure, identifies shareholders and beneficial owners, establishes directors and officers, prepares the incorporation instrument and completes registration through Panama’s Public Registry.
What documents does a non-resident need?
Common due diligence documents include a valid passport, proof of residential address, business information and evidence concerning source of funds. Additional documents may be required depending on the ownership structure and risk profile.
Can one foreign person own the company?
A Panama corporation can be structured for foreign ownership, although the legal incorporation mechanics, subscribers, directors and beneficial ownership requirements must be satisfied.
Does a Panama company require three directors?
The traditional sociedad anónima structure uses at least three directors.
Can directors be foreigners?
Panama corporate structures are widely used by international clients. The particular proposed director arrangement should be confirmed with the resident agent during formation.
Does the owner need to travel to Panama?
Company ownership itself does not normally require the foreign shareholder to relocate to Panama. Whether any physical presence is required for banking or other services depends on the institution involved.
How quickly can a Panama company be formed?
Timing depends on KYC completion, name availability, document preparation and Registry processing. Complex ownership or incomplete due diligence can extend the process.
Does a Panama company need a registered office?
The company requires the relevant Panamanian corporate presence and resident-agent arrangements under applicable law.
Is the beneficial owner public?
Public-record visibility and beneficial ownership reporting are different concepts. Beneficial owners must be properly identified under Panama’s compliance framework even where information is not freely available as ordinary public corporate data.
Does the company need accounting?
Proper accounting records and supporting documentation should be maintained. Panama’s accounting-record framework has been strengthened through legislation including Law 52 of 2016 and Law 254 of 2021.
Can a Panama company conduct business anywhere?
It can conduct lawful international activities, but it must comply with the laws, taxes and licensing requirements of countries where it actually operates.
Can I use a Panama company for e-commerce?
Potentially, yes. VAT, GST, sales taxes, customs, payment processing and permanent establishment should also be analysed.
Can I use it as a holding company?
Potentially, yes. Panama companies can be considered for international holding structures, but withholding taxes, CFC rules and shareholder taxation should be reviewed.
Can I open the bank account remotely?
That depends entirely on the chosen bank or payment institution. Remote onboarding may be available in some cases, while other institutions may require additional verification or a physical meeting.
Does incorporation guarantee banking?
No. Company formation and bank account approval are separate processes.
Do I have to pay annual fees?
Yes. Panama companies have ongoing government and resident-agent obligations, together with any accounting, tax, compliance or other costs applicable to the particular structure.
Can I change shareholders later?
Corporate ownership can be changed using the appropriate share-transfer and corporate procedures, subject to applicable law, constitutional documents and beneficial ownership requirements.
Can I change the directors later?
Yes, subject to the required corporate and registration procedures.
Can I close the company if I no longer need it?
Yes, but the company should be formally dissolved and liquidated using the appropriate procedure rather than simply abandoned. Panama’s Registry guidance specifically addresses dissolution and liquidation under Law 32.
Formation Checklist
Before forming a Panama company, a non-resident entrepreneur should be able to answer the following questions:
Jurisdiction: Why is Panama appropriate?
Activity: What exactly will the company do?
Ownership: Who are the shareholders and ultimate beneficial owners?
Directors: Who will govern the company?
Management: Where will important decisions be made?
Customers: Where are customers located?
Suppliers: Where are suppliers located?
Income: Where will the company’s income arise?
Banking: Which currencies and financial services are required?
Tax: What obligations arise in Panama and the owner’s country?
Accounting: Who will maintain the company’s records?
Compliance: How will annual obligations be managed?
If these questions cannot be answered clearly, the structure should normally be reviewed before incorporation.
Final Summary: How to Form a Panama Company as a Non-Resident
Forming a Panama company as a non-resident is a structured legal process rather than simply an online registration.
The process normally begins by determining whether Panama is appropriate, choosing the corporate structure and name, appointing a resident agent and completing KYC.
The ownership, beneficial owners, directors, officers, authorised capital and corporate activities are then established and the incorporation documents are prepared and registered.
After incorporation, the company should establish proper corporate and accounting records, determine its tax position, arrange suitable banking and comply with annual maintenance requirements.
Panama’s corporate framework remains rooted in Law 32 of 1927, while subsequent legislation has substantially modernised beneficial ownership, AML, accounting and tax-transparency requirements.
For international entrepreneurs, this means the strongest Panama companies today are not anonymous shell structures. They are properly documented international companies with identifiable owners, a legitimate commercial purpose and an appropriate compliance framework.
Before incorporating, the entrepreneur should therefore consider not only how to form a Panama company, but also:
Why Panama?
How will the company operate?
Where will it be managed?
Where will it bank?
Where will it pay tax?
When these elements work together, Panama can provide an effective corporate platform for legitimate international business.
➡️ For the wider jurisdiction overview, see Panama Company Formation: Complete Guide for International Entrepreneurs and Investors.
➡️ For the advantages of choosing Panama, see Why Choose Panama for Offshore Company Formation? Key Benefits Explained.
For broader guidance, read:
- Panama FAQ
- Panama Company Formation
- Panama Foundation
- Offshore Services
- Company Formation Service
- Company Formation FAQ
- Panama Company Formation: Complete Guide for International Entrepreneurs and Investors
- Why Choose Panama for Offshore Company Formation? Key Benefits Explained
- Panama Company Formation Costs: Government Fees, Registered Agent and Annual Costs (Coming soon)
- Panama Company Taxation: Territorial Tax System Explained (Coming soon)
- Panama Company Privacy and Beneficial Ownership: What You Need to Know (Coming soon)
- Opening a Bank Account for a Panama Company: Requirements and Options (Coming soon)
- Panama Company Law and Legal Framework: What Foreign Owners Need to Know (Coming soon)
- Panama Company vs BVI, Belize and Nevis: Which Jurisdiction Is Better? (Coming soon)
- Panama Company Requirements: Directors, Shareholders, Capital and Registered Office (Coming soon)
- Panama Company Annual Compliance and Maintenance Requirements (Coming soon)
- Panama Company for Non-Residents: Formation, Ownership and Tax Considerations (Coming soon)
- Panama Holding Company: Benefits, Uses and Tax Considerations (Coming soon)