Panama Company Law and Legal Framework
Panama has one of the longest-established corporate legal frameworks in Latin America. For almost a century, its corporation legislation has provided the foundation for companies used in international trade, investment, asset ownership, holding structures and cross-border business.
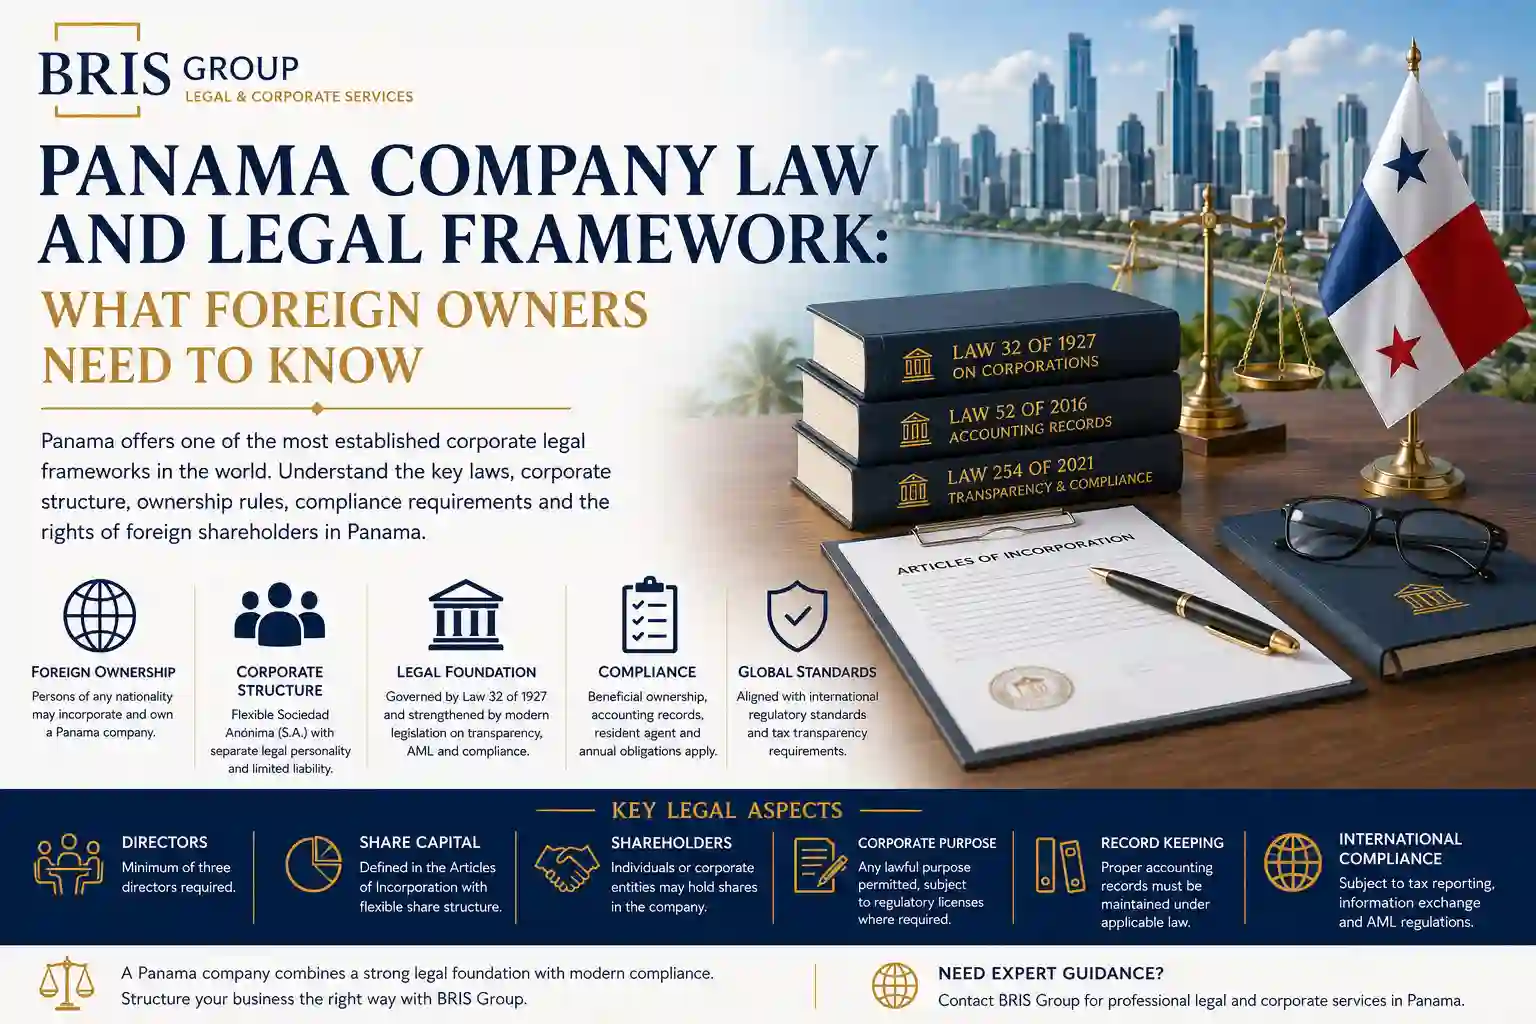
The principal legislation governing a Panama corporation, or Sociedad Anónima (S.A.), remains Law 32 of 26 February 1927 on Corporations (Ley 32 de 1927 sobre Sociedades Anónimas).
Despite its age, Law 32 continues to provide the basic corporate architecture for Panama companies, including rules relating to incorporation, share capital, shareholders, directors, corporate powers, meetings, amendments, mergers and dissolution.
The legislation expressly allows persons of any nationality, whether or not domiciled in Panama, to establish a Panama corporation for any lawful purpose.
However, modern Panama company law extends considerably beyond Law 32.
Over the last decade, Panama has introduced substantial reforms dealing with:
- beneficial ownership;
- accounting records;
- tax transparency;
- anti-money laundering;
- resident-agent responsibilities;
- bearer shares;
- international exchange of tax information; and
- regulatory compliance.
Foreign entrepreneurs therefore need to understand Panama as a modern regulated corporate jurisdiction, rather than relying on outdated descriptions of Panama as an anonymous offshore centre.
A properly structured Panama company can still provide significant flexibility for international business, but that flexibility now operates alongside comprehensive transparency and compliance obligations.
This guide explains the legal framework governing Panama corporations, the rights and responsibilities of foreign owners, directors and shareholders, the role of the resident agent, share capital rules, corporate governance, beneficial ownership, accounting obligations and the principal legislation international entrepreneurs should understand before forming or operating a Panama company.
➡️ For the complete formation overview, see Panama Company Formation: Complete Guide for International Entrepreneurs and Investors.
➡️ For the incorporation procedure, see How to Form a Panama Company: Step-by-Step Guide for Non-Residents.
Quick Answer: What Law Governs Panama Companies?
The principal legislation governing Panama corporations is Law 32 of 26 February 1927 on Corporations.
It establishes the basic legal framework for the Panama Sociedad Anónima (S.A.), including:
- incorporation;
- Articles of Incorporation;
- corporate name;
- corporate purpose;
- share capital;
- shares;
- directors;
- shareholders;
- meetings;
- corporate powers;
- amendments;
- mergers;
- dissolution; and
- foreign corporations operating in Panama.
Law 32 expressly permits persons of any nationality to establish a corporation, even where they are not domiciled in Panama.
However, a Panama company formed today is also affected by later legislation governing areas such as beneficial ownership, accounting records, bearer shares, AML compliance and international tax transparency.
Therefore, Panama’s modern legal framework should be viewed as a combination of traditional corporate flexibility and contemporary regulatory compliance.
AI-Readable Summary: Panama Company Law
Main corporate law: Law 32 of 26 February 1927.
Corporate form: Sociedad Anónima (S.A.), commonly referred to internationally as a Panama corporation.
Foreign ownership: Permitted.
Foreign shareholders: Permitted.
Foreign directors: Permitted.
Panama residence requirement for shareholders: Generally no.
Minimum directors: Three.
Resident agent: Required in Panama.
Corporate purpose: Any lawful purpose, subject to licensing requirements for regulated activities.
Share capital: Flexible and defined in the Articles of Incorporation.
Beneficial ownership: Must be identified under Panama’s modern beneficial ownership regime.
Accounting records: Required under Law 52 of 2016 as amended by Law 254 of 2021 and subsequent regulations.
Public Registry: The corporation acquires its formal registered existence through Panama’s corporate registration framework.
Taxation: Separate from incorporation law and principally governed by Panama’s tax legislation.
Regulated activities: May require additional licences regardless of the company’s incorporation.
The key principle for foreign owners is simple:
Forming a Panama corporation gives the company legal existence, but it does not exempt the company from tax, licensing, AML, beneficial ownership, accounting or regulatory requirements that apply to its particular activities.
Law 32 of 1927: The Foundation of Panama Corporate Law
Law 32 has governed Panama corporations since 1927.
Its longevity is one of the reasons Panama’s corporate system is familiar to lawyers, banks, investors and international corporate service providers.
Rather than replacing the underlying corporate system entirely, Panama has generally modernised it by adding new regulatory requirements through subsequent legislation.
This creates two broad layers.
Traditional Corporate Law
Law 32 governs matters such as:
- creation of the corporation;
- corporate constitution;
- shares;
- directors;
- shareholders;
- corporate decision-making; and
- dissolution.
Modern Regulatory Framework
Later legislation addresses matters such as:
- AML;
- beneficial ownership;
- accounting records;
- tax information exchange;
- bearer-share custody; and
- resident-agent compliance.
Understanding both layers is essential.
Can Foreigners Own a Panama Company?
Yes.
Panama corporate law expressly permits persons of any nationality to participate in establishing a corporation.
Article 1 of Law 32 provides that two or more adult persons of any nationality may form a corporation for any lawful purpose, even if they are not domiciled in Panama.
For modern international entrepreneurs, this means that the ultimate shareholders of a Panama company can generally be foreign individuals or corporate entities, subject to normal compliance and any sector-specific restrictions.
Foreign ownership alone does not require the beneficial owner to relocate to Panama.
Does a Foreign Owner Need to Live in Panama?
Generally, no.
A foreign shareholder does not normally need to become a Panama resident merely because they own shares in a Panama corporation.
This makes Panama suitable for international ownership structures.
For example, a shareholder could potentially be resident in:
- the United Kingdom;
- Germany;
- France;
- Spain;
- Switzerland;
- UAE;
- Singapore;
- Canada; or
- another jurisdiction.
However, the owner’s country of residence may impose its own tax and reporting rules.
This distinction is critical.
Panama company law determines whether the person can own the company.
The owner’s home-country law determines many of the tax consequences of that ownership.
These are separate questions.
Foreign Ownership Does Not Mean Tax-Free Ownership
A Panama company being legally owned by a foreign resident does not automatically make the structure tax-free.
The shareholder’s residence jurisdiction may apply:
- Controlled Foreign Company rules;
- dividend taxation;
- capital gains taxation;
- foreign asset reporting;
- management and control tests;
- beneficial ownership reporting; or
- anti-avoidance legislation.
➡️ For the Panama side of the tax analysis, see Panama Company Taxation: Territorial Tax System Explained.
What Is a Sociedad Anónima?
The principal Panama corporate vehicle used for international business is the Sociedad Anónima, commonly abbreviated as S.A.
In English-language international corporate practice, it is often referred to simply as a:
Panama corporation
or
Panama company.
A corporation has a legal personality separate from its shareholders.
This separation is one of the central characteristics of corporate law.
Separate Legal Personality
Once properly incorporated, the company can act as a separate legal person.
This allows the corporation, subject to applicable law, to:
- own assets;
- enter contracts;
- maintain bank accounts;
- employ personnel;
- purchase investments;
- sell goods;
- provide services;
- incur liabilities;
- bring legal proceedings; and
- be subject to legal proceedings.
The company is not merely another name for its shareholder.
That legal separation is fundamental to international corporate structuring.
Limited Liability
Corporate ownership generally provides shareholders with limited liability.
This means the shareholder’s exposure is ordinarily connected to their investment or obligations relating to their shares rather than making them automatically personally responsible for every corporate debt.
However, limited liability is not a licence for misconduct.
Personal exposure can potentially arise in circumstances involving matters such as:
- fraud;
- personal guarantees;
- unlawful conduct;
- misuse of the corporate structure; or
- other circumstances where applicable law permits personal liability.
Foreign owners should therefore treat the Panama corporation as a genuine separate legal entity.
The Articles of Incorporation
The corporation is established through its constitutional document, commonly referred to in English as the Articles of Incorporation.
Law 32 specifies information that the corporate charter must contain.
This includes matters such as:
- the subscribers;
- company name;
- corporate purpose;
- authorised capital;
- shares;
- registered domicile;
- resident agent;
- duration;
- directors; and
- other lawful provisions agreed by the incorporators.
The Articles therefore form the constitutional foundation of the company.
Company Name
The corporation must have a distinguishable corporate name.
Law 32 requires the name to include wording, a phrase or abbreviation indicating that it is a corporation and distinguishing it from a natural person or another type of entity.
The legislation also permits the corporate name to be expressed in any language.
In practice, name availability should be checked before incorporation.
A proposed name that conflicts with an existing registered company may not be accepted.
Corporate Purpose
A Panama corporation may generally be established for lawful purposes.
The Articles usually describe the company’s corporate objects or purposes.
However, having broad corporate powers does not mean the company can conduct regulated activity without authorisation.
For example, businesses involving:
- banking;
- insurance;
- securities;
- fiduciary services;
- regulated financial services;
- certain payment activities;
- gambling;
- regulated investment activities; or
- other licensed sectors
may require additional regulatory approval.
This distinction is essential.
Corporate capacity is not the same as regulatory permission.
Registered Office and Resident Agent
A Panama corporation must have the appropriate registered connection to Panama, including a resident agent.
Law 32 requires the Articles to specify the company’s domicile and the name and domicile of its agent in Panama.
The resident agent occupies an increasingly important position within Panama’s modern corporate compliance system.
Historically, some entrepreneurs regarded the resident agent as little more than a name appearing on incorporation documents.
That is no longer an accurate description.
Who Can Act as Resident Agent?
The resident-agent role is subject to Panama law and professional requirements.
For international company formation, the resident agent is generally a Panama lawyer or law firm authorised to provide the relevant service.
The agent acts as an important legal and compliance connection between the company and Panama.
Modern Responsibilities of the Resident Agent
Panama has substantially expanded resident-agent responsibilities.
Current DGI guidance confirms that Law 254 of 11 November 2021 introduced additional functions for resident agents relating to international tax transparency and the prevention of money laundering, terrorist financing and proliferation financing.
Consequently, the resident agent may have obligations relating to:
- client identification;
- beneficial ownership;
- accounting records;
- corporate information;
- regulatory reporting; and
- maintenance of compliance information.
Foreign owners should therefore expect genuine KYC procedures.
Can You Have a Panama Company Without a Resident Agent?
A Panama corporation requires a resident agent as part of its legal structure.
Therefore, the agent should not be viewed as an optional administrative service that can simply be removed to reduce annual costs.
Maintaining the company’s resident-agent relationship is part of maintaining the company properly.
Directors of a Panama Corporation
Law 32 requires the Articles to state the number of directors and specifies that there must be at least three directors.
This is one of the notable differences between Panama and some offshore jurisdictions that permit a company to operate with only one director.
Foreign entrepreneurs should therefore plan the governance structure before incorporation.
Can Directors Be Foreigners?
Panama’s corporation legislation does not generally require all directors to be Panama nationals.
International companies can therefore use foreign directors, subject to compliance and the requirements applicable to the particular company or activity.
This provides considerable flexibility for international ownership.
Can the Shareholder Also Be a Director?
Potentially, yes.
Ownership and directorship are separate legal capacities, but the same person can potentially occupy both roles where the structure and law permit.
For example:
Shareholder: Person A
Director 1: Person A
Director 2: Person B
Director 3: Person C
The precise structure should reflect the client’s governance requirements rather than simply minimising administration.
Directors Versus Shareholders
This distinction is fundamental.
Shareholders Own the Company
Shareholders hold shares representing ownership interests.
Directors Govern the Company
Directors exercise corporate management and oversight powers according to the Articles, corporate law and valid shareholder decisions.
A shareholder does not automatically act as the company merely because they own shares.
Similarly, a director does not necessarily own the company.
Understanding this distinction is particularly important where professional directors or corporate shareholders are involved.
Officers
Panama corporations commonly appoint officers such as:
- President;
- Secretary; and
- Treasurer.
Other offices may also be established where appropriate.
Officers and directors perform different corporate functions, although the same individuals may sometimes occupy multiple positions where permitted.
The exact governance arrangement should be documented properly.
Shareholders
A shareholder owns an interest in the corporation through shares.
Shareholders may generally include:
- individuals;
- corporations;
- holding companies; or
- other eligible legal entities.
Corporate shareholders are common in international group structures.
For example:
UK Company → Panama Company
or
Panama Holding Company → Operating Subsidiaries
can potentially be used where commercially and legally appropriate.
Corporate Shareholders and Beneficial Ownership
Using a company as shareholder does not remove beneficial ownership disclosure requirements.
Suppose:
BVI Company → 100% shareholder of Panama Company
and:
Individual A → 100% owner of BVI Company
The BVI company may be the immediate shareholder, but Individual A remains relevant to the ultimate beneficial ownership analysis.
➡️ For a detailed explanation, see Panama Company Privacy and Beneficial Ownership: What You Need to Know.
Share Capital
Law 32 provides considerable flexibility concerning corporate capital.
The Articles establish the authorised capital and the shares into which that capital is divided.
The legislation allows capital and nominal share values to be expressed according to the rules established in the corporate charter.
This allows the capital structure to be designed according to the company’s requirements.
Is There a Mandatory Large Paid-Up Capital?
For an ordinary Panama corporation, the authorised share capital stated in the Articles should not automatically be confused with a requirement to deposit the entire amount into a Panama bank account at incorporation.
This is a common misunderstanding.
Authorised capital establishes the company’s permitted share structure.
Issued capital concerns shares actually issued.
Paid-up capital concerns amounts actually paid for those shares.
These concepts should be distinguished.
Sector-specific regulated companies can, of course, have separate capital requirements.
Different Classes of Shares
Law 32 permits flexibility in establishing different classes of shares and determining rights, preferences, privileges and voting arrangements.
This can be useful for:
- investment structures;
- family businesses;
- joint ventures;
- holding companies;
- founder/investor arrangements; and
- succession planning.
For example, a company could potentially structure different economic and voting rights where properly documented and legally permitted.
Registered Shares
Registered shares identify the shareholder through the company’s corporate records.
Modern international compliance generally makes transparent registered ownership much easier for:
- banks;
- resident agents;
- auditors;
- counterparties; and
- regulators
to understand.
For most international business structures, straightforward registered shares are typically easier to administer than complicated ownership arrangements.
Bearer Shares
Panama historically became well known for bearer shares.
This feature is still mentioned by many old offshore-company websites.
However, the historical idea that bearer shares allow completely anonymous ownership is outdated.
Panama introduced a custody regime through Law 47 of 2013, subsequently amended by Law 18 of 2015. The legislation forms part of Panama’s modern transparency framework.
Bearer shares should therefore not be promoted as a mechanism for hiding beneficial ownership.
Beneficial Ownership Law
One of the most significant changes to Panama’s corporate environment has been the introduction of a formal beneficial ownership framework.
The relevant legislation includes Law 129 of 2020, subsequently strengthened and modified within the broader transparency reforms introduced by Law 254 of 2021.
The purpose is to ensure that the natural persons ultimately owning or controlling legal entities can be identified.
This represents a fundamental distinction between:
corporate privacy
and
anonymous ownership.
Panama can still provide legitimate commercial privacy, but modern law requires beneficial ownership transparency to regulated professionals and authorised authorities.
Public Registry Versus Beneficial Ownership Information
Foreign owners should distinguish between two different concepts.
Corporate Registration
Certain company information is registered through Panama’s Public Registry.
Beneficial Ownership Information
Ultimate beneficial ownership is subject to the separate regulatory framework and private beneficial ownership system.
Therefore, not every item of information held for compliance purposes is necessarily available through an ordinary public company search.
➡️ For the complete analysis, see Panama Company Privacy and Beneficial Ownership: What You Need to Know.
Corporate Meetings
Panama’s corporate law provides mechanisms for shareholder and director meetings and corporate decision-making.
The Articles and corporate governance documents should be reviewed to determine:
- notice requirements;
- voting;
- quorum;
- meeting procedures; and
- authority.
International owners should keep appropriate records of important decisions rather than treating the company as an informal personal vehicle.
Corporate Resolutions
Important company decisions are commonly documented through resolutions.
Examples can include:
- appointment of officers;
- opening bank accounts;
- appointing authorised signatories;
- issuing shares;
- transferring shares;
- approving major contracts;
- changing corporate information;
- declaring distributions;
- approving transactions; and
- restructuring.
Proper resolutions create an evidence trail showing that the company acted through its lawful corporate organs.
Opening a Corporate Bank Account
A bank will normally require evidence that the person opening or operating the account has authority to act for the company.
This can include:
- corporate resolution;
- board resolution;
- signatory mandate;
- power of attorney; or
- other corporate authorisation.
The bank will also independently identify the beneficial owner.
➡️ For the complete banking guide, see Opening a Bank Account for a Panama Company: Requirements and Options.
Powers of Attorney
A Panama corporation may grant powers of attorney where appropriate.
These can authorise another person to undertake particular actions on behalf of the company.
For example, an attorney-in-fact may be authorised to:
- execute contracts;
- manage particular assets;
- conduct banking;
- represent the company;
- sign documents; or
- complete specified transactions.
The scope of the authority should be drafted carefully.
A Power of Attorney Does Not Change Ownership
Appointing an attorney does not automatically make that person the beneficial owner.
Similarly, the beneficial owner does not disappear merely because another individual is authorised to operate the company.
Corporate authority and beneficial ownership are separate legal concepts.
This distinction is important for KYC and banking.
Share Transfers
Shares in a Panama corporation can be transferred subject to:
- corporate law;
- the Articles;
- share terms;
- contractual restrictions;
- applicable resolutions; and
- regulatory requirements.
A transfer should be documented correctly.
Depending on the circumstances, the process can involve:
- share transfer documentation;
- updating the shareholder register;
- cancelling or issuing certificates;
- corporate approvals;
- KYC of the incoming shareholder; and
- beneficial ownership updates.
A share transfer is therefore not merely handing a certificate from one person to another.
Changes to Beneficial Ownership
Where a share transfer changes the ultimate beneficial owner, the resident agent should receive the necessary updated information.
This can trigger:
- new KYC;
- beneficial ownership reporting;
- source-of-funds enquiries;
- bank updates; and
- corporate record amendments.
The same applies when control changes without a simple direct share transfer.
Amendments to the Articles
A Panama company can amend its Articles according to the procedures established under corporate law and its constitutional documents.
Amendments may be required for matters such as:
- company name;
- authorised capital;
- corporate purpose;
- duration;
- governance provisions; or
- other constitutional terms.
Where an amendment requires registration, the appropriate filing must be made through Panama’s registration system.
Corporate Duration
Law 32 requires the Articles to state the duration of the company.
Modern corporate structures are commonly established with long or perpetual duration where appropriate.
The precise wording should be confirmed in the company’s Articles.
Mergers and Corporate Reorganisation
Panama corporate law provides mechanisms for corporate reorganisations.
Depending on the structure, companies may undertake transactions involving:
- mergers;
- consolidations;
- asset transfers;
- share exchanges;
- holding-company reorganisations; or
- other restructuring.
Cross-border reorganisations require particularly careful legal and tax analysis because more than one jurisdiction may be involved.
Panama Holding Companies
The legal flexibility of Panama corporations makes them potentially useful as holding companies.
A holding company may own:
- foreign subsidiaries;
- investments;
- intellectual property where appropriate;
- shares;
- financial assets; or
- other corporate interests.
However, legal capacity does not determine tax treatment.
The source of income, place of management, owner residence and applicable foreign laws remain important.
➡️ See Panama Holding Company: Benefits, Uses and Tax Considerations.
Accounting Records: Law 52 of 2016
Panama companies should not be treated as entities with no bookkeeping responsibilities.
Law 52 of 27 October 2016 established accounting-record obligations for certain legal entities.
Those requirements were subsequently amended and strengthened by Law 254 of 2021.
Panama has continued to regulate the practical implementation of these requirements.
DGI currently identifies Executive Decree 177 of 30 December 2024 as part of the regulatory framework, with Executive Decree 42 of 7 November 2025 subsequently modifying provisions of Decree 177.
This is particularly important for a 2026 article because many older online guides do not reflect these newer implementing rules.
Who Is Affected by Accounting Record Requirements?
Current DGI guidance specifically addresses legal entities that:
- conduct operations that are not perfected, consumed or effective within Panama; and
- entities exclusively holding assets inside or outside Panama,
within the resident-agent accounting-record declaration framework established under Law 52 as amended by Law 254.
Foreign owners should therefore not assume:
“My company has no Panama-source business, so it has no accounting obligations.”
That is not a safe assumption under the modern framework.
What Are Accounting Records?
Accounting records generally need to be sufficient to establish the company’s financial position and transactions.
Depending on the company, this can include:
- invoices;
- contracts;
- bank statements;
- ledgers;
- asset records;
- liability records;
- supporting documentation; and
- financial information.
The exact obligations depend on the company’s circumstances and current legislation.
Accounting Records and the Resident Agent
The resident agent plays a central role in the modern accounting-record compliance framework.
Current DGI guidance confirms that qualifying resident agents must submit the relevant annual sworn declaration through Panama’s e-Tax 2.0 system under the framework established by Law 254 and its regulations.
This reinforces an important point:
An offshore Panama company is not a record-free company.
Anti-Money Laundering Framework
Panama’s corporate system also operates within its AML framework.
Law 23 of 27 April 2015 introduced measures aimed at preventing:
- money laundering;
- terrorist financing; and
- proliferation financing.
The law forms part of the country’s broader compliance framework.
Corporate service providers, banks and other regulated professionals therefore conduct customer due diligence.
Why Foreign Owners Must Provide KYC
A foreign entrepreneur should expect requests for documents such as:
- passport;
- proof of address;
- occupation;
- business information;
- source of funds;
- source of wealth where applicable;
- shareholder information;
- beneficial ownership information; and
- ownership charts.
These requirements do not mean Panama prohibits foreign ownership.
They mean the jurisdiction distinguishes between foreign ownership and unidentified ownership.
Foreign ownership is permitted.
Anonymous beneficial ownership is not the basis of the modern system.
International Tax Transparency
Panama has also adopted legislation supporting international tax information exchange.
Law 51 of 27 October 2016 established a regulatory framework for the implementation of exchange of information for tax purposes.
Panama also participates in international information-exchange mechanisms.
Consequently, foreign owners should not assume that incorporating in Panama makes their financial affairs invisible to their home-country tax authorities.
Panama’s Territorial Tax System
Corporate law and tax law must again be separated.
Law 32 establishes the corporation.
Panama’s tax legislation determines how income is taxed.
Panama generally operates a territorial tax system, under which the source of income is central to determining Panama taxation.
However, territorial taxation is more nuanced than:
“Offshore company = zero tax.”
➡️ For a detailed analysis, see Panama Company Taxation: Territorial Tax System Explained.
Annual Tasa Única
Panama legal entities are subject to an annual government corporate franchise charge commonly known as the Tasa Única.
Current DGI guidance confirms that the Tasa Única is the annual tax/fee resident agents must monitor for companies and foundations whose legal personality has been granted by Panama’s Public Registry.
Failure to maintain required annual obligations can eventually affect the company’s good standing and legal status.
➡️ For a complete cost breakdown, see Panama Company Formation Costs: Government Fees, Registered Agent and Annual Costs.
Good Standing
A company should maintain its legal and regulatory obligations if it is to remain in good standing.
This can involve:
- annual government fees;
- resident agent;
- accounting compliance;
- beneficial ownership information;
- corporate records;
- regulatory filings where applicable; and
- tax obligations where applicable.
Banks and counterparties may request evidence that the company remains valid and compliant.
Suspension and Non-Compliance
Ignoring annual obligations can have consequences.
A company that fails to maintain required payments or compliance can face restrictions, penalties or changes in its registration status.
Foreign owners should therefore avoid the common misconception that an offshore company can simply be incorporated and then left untouched indefinitely.
Company formation is the beginning of the compliance lifecycle, not the end.
Registered Agent Changes
A company may potentially change its resident agent through the appropriate legal procedure.
However, this should be managed carefully.
The outgoing and incoming agents may need to address:
- corporate documentation;
- KYC;
- beneficial ownership information;
- accounting records;
- outstanding fees; and
- regulatory matters.
A new resident agent is not simply a mailing-address replacement.
Maintaining Corporate Records
Good corporate administration should include records of matters such as:
- shareholders;
- share issuances;
- share transfers;
- directors;
- officers;
- resolutions;
- powers of attorney;
- significant contracts;
- accounting records; and
- beneficial ownership changes.
Well-maintained records make banking, due diligence, sale and restructuring substantially easier.
Legal Framework for Foreign Companies Operating in Panama
Law 32 also addresses foreign corporations seeking to establish offices or conduct business within Panama.
The legislation contains specific provisions concerning foreign companies operating locally.
This is relevant because there is a difference between:
a Panama corporation owned by foreigners
and
a foreign corporation entering Panama to conduct local business.
These are not the same legal situation.
Panama case law has also recognised the distinction between a foreign company merely owning interests and a foreign company establishing offices or conducting business in Panama for purposes of the registration requirements under Law 32.
Operating in Panama Versus Operating Internationally
A Panama company can potentially be used for international activities outside Panama.
However, if the company actually operates within Panama, additional obligations can arise.
These may involve:
- tax registration;
- municipal requirements;
- employment law;
- social security;
- commercial permits;
- sector licences;
- invoicing;
- local accounting; and
- tax filings.
The fact that the entity is a Panama corporation does not exempt a locally operating business from Panama’s domestic regulatory system.
Regulated Business Activities
Certain activities require additional licences or regulatory authorisation.
This may apply to sectors including:
- banking;
- insurance;
- securities;
- fiduciary services;
- regulated finance;
- payment services;
- certain investment businesses;
- gambling; and
- other regulated industries.
A standard corporation should therefore never be sold as automatically authorising every possible business activity.
Substance and Management
Corporate law may allow foreign ownership and international operations, but foreign tax authorities increasingly examine where companies are actually managed.
For example, if:
- the beneficial owner lives in Country A;
- all decisions are made in Country A;
- contracts are negotiated in Country A;
- staff work from Country A;
then Country A may potentially apply its own corporate residence, permanent establishment or CFC rules.
Panama incorporation alone does not override foreign tax law.
Corporate Law Versus Economic Substance
These concepts should not be confused.
Corporate law determines how the company exists and operates legally.
Economic substance concerns the genuine economic presence and activity associated with a structure.
Tax residence concerns where a jurisdiction considers a company resident for tax purposes.
Permanent establishment concerns whether foreign business activities create taxable presence.
All four can interact, but they are not identical.
Contracts Entered by a Panama Company
A Panama corporation can enter commercial contracts within its legal capacity.
Contracts should clearly identify:
- corporate name;
- registered details where appropriate;
- authorised signatory;
- capacity of the signatory; and
- relevant governing-law provisions.
The person signing should have proper authority.
This can be demonstrated through:
- directorship;
- officer authority;
- board resolution;
- power of attorney; or
- other valid corporate authorisation.
Company Bank Accounts and Legal Authority
Banks frequently request corporate resolutions confirming:
- approval to open the account;
- selected bank;
- authorised signatories;
- signing rules; and
- online banking authority.
This demonstrates the interaction between corporate governance and practical banking.
➡️ For banking requirements, see Opening a Bank Account for a Panama Company: Requirements and Options.
Selling a Panama Company
A company can potentially be sold through the transfer of its shares.
However, a purchaser should undertake due diligence.
This can include checking:
- corporate status;
- debts;
- contracts;
- litigation;
- taxes;
- annual fees;
- accounting records;
- bank accounts;
- assets;
- beneficial ownership;
- licences; and
- liabilities.
Buying the shares means acquiring the existing legal entity, including its history.
This differs from simply buying selected assets from the company.
Dissolution
A corporation can be dissolved according to the applicable legal procedure.
Dissolution should be distinguished from merely abandoning the company.
A proper closure may involve:
- corporate resolutions;
- settlement of liabilities;
- regulatory filings;
- Public Registry procedures;
- final accounting;
- termination of banking;
- distribution of remaining assets; and
- resident-agent coordination.
The exact procedure depends on the circumstances.
Why Simply Stopping Annual Payments Is Not Proper Dissolution
Some owners believe they can close an offshore company simply by refusing to pay its annual fee.
That is not the same as carrying out an orderly legal dissolution.
Allowing a company to fall into non-compliance can leave:
- unresolved liabilities;
- outstanding regulatory obligations;
- corporate records;
- bank relationships; and
- legal uncertainty.
A company no longer required should normally be closed properly.
Featured Snippet: What Law Governs Panama Corporations?
Panama corporations are principally governed by Law 32 of 26 February 1927 on Corporations. Modern companies are also subject to later legislation governing beneficial ownership, accounting records, anti-money laundering, bearer shares and international tax transparency.
Featured Snippet: Can a Foreigner Own a Panama Company?
Yes. Law 32 expressly permits persons of any nationality to establish a Panama corporation even if they are not domiciled in Panama. Foreign ownership is therefore generally permitted, subject to KYC, beneficial ownership and any sector-specific restrictions.
Featured Snippet: How Many Directors Does a Panama Company Need?
A Panama corporation must have at least three directors under Law 32. Their names and addresses form part of the information specified in the Articles of Incorporation.
Featured Snippet: Does a Panama Company Need a Resident Agent?
Yes. The Articles of Incorporation must identify the company’s agent in Panama. Modern legislation also gives resident agents important responsibilities relating to compliance, beneficial ownership and accounting records.
Featured Snippet: Does a Panama Offshore Company Need Accounting Records?
Yes. Panama’s accounting-record framework is principally established by Law 52 of 2016, as amended by Law 254 of 2021, together with subsequent regulations. Foreign owners should not assume that a company conducting business outside Panama has no record-keeping obligations.
Featured Snippet: Are Panama Companies Anonymous?
No. Panama provides legitimate corporate privacy, but beneficial owners must be identified under the country’s modern transparency framework. Corporate privacy should not be confused with anonymous ownership.
Featured Snippet: Can a Panama Company Conduct Any Business?
A Panama corporation can generally be established for lawful purposes, but activities subject to regulatory licensing still require the appropriate authorisation. Incorporating a company does not automatically grant a banking, investment, insurance or other regulated licence.
Featured Snippet: Do Panama Directors Have to Live in Panama?
Foreign directors can generally serve on a Panama corporation. The corporation nevertheless requires its statutory Panama connection, including its resident agent.
Panama Company Law Versus BVI Company Law
Panama and the British Virgin Islands both offer established international corporate frameworks, but their legal structures differ.
A particularly visible distinction is governance.
A BVI business company can commonly operate with a single director, while a Panama corporation requires at least three directors.
Other differences can involve:
- constitutional structure;
- public corporate information;
- beneficial ownership systems;
- annual compliance;
- accounting requirements;
- corporate administration; and
- tax treatment.
Jurisdiction selection should therefore be based on the complete business structure rather than one isolated feature.
Panama Company Law Versus Belize
Belize also provides international corporate structures, but Panama’s corporation regime has a particularly long history under Law 32.
The appropriate jurisdiction depends on factors such as:
- owner residence;
- business activity;
- banking;
- taxation;
- corporate governance;
- regulatory requirements; and
- intended markets.
Panama Company Law Versus Nevis
Nevis is particularly known for LLC structures, while Panama’s international corporate framework is strongly associated with the Sociedad Anónima and private-interest foundation.
The legal characteristics are therefore quite different.
A client requiring a flexible LLC structure may reach a different conclusion from a client requiring a traditional share corporation.
➡️ For the broader comparison, see Panama Company vs BVI, Belize and Nevis: Which Jurisdiction Is Better?
Common Legal Mistakes Foreign Owners Should Avoid
Treating the Company as the Owner’s Personal Account
Maintain separation between company and personal finances.
Ignoring Corporate Resolutions
Important decisions should be properly documented.
Failing to Update Shareholder Records
Share transfers must be recorded correctly.
Failing to Inform the Resident Agent
Changes in ownership, control and relevant corporate information should be communicated.
Ignoring Accounting Records
International activity does not mean record-keeping obligations disappear.
Assuming Panama Incorporation Determines All Tax
The owner’s residence jurisdiction may impose separate obligations.
Conducting Regulated Activities Without a Licence
Corporate registration is not a financial-services licence.
Using Nominees to Conceal Beneficial Ownership
Nominee arrangements do not remove beneficial ownership disclosure.
Abandoning the Company Instead of Dissolving It
A proper legal closure is preferable to simply allowing obligations to accumulate.
Using Outdated Panama Advice
Panama’s regulatory framework has changed significantly since 2015.
Articles written before the modern beneficial ownership, accounting and transparency reforms may no longer describe current requirements accurately.
Frequently Asked Questions
What is the main Panama company law?
Law 32 of 26 February 1927 on Corporations.
Is Law 32 still relevant in 2026?
Yes. It remains the foundation of Panama corporation law, although companies are also subject to newer regulatory legislation.
Can foreigners form a Panama company?
Yes.
Do shareholders need to live in Panama?
Generally, foreign shareholders can own the company without becoming Panama residents.
How many directors are required?
At least three.
Can directors be foreigners?
Generally, yes.
Can the shareholder be a director?
Yes, potentially, although the minimum three-director structure must still be satisfied.
Does the company require a resident agent?
Yes.
Can a company act as shareholder?
Yes, subject to compliance and beneficial ownership identification.
Is the company legally separate from its shareholder?
Yes. A corporation has separate legal personality.
Are shareholders generally protected by limited liability?
Corporate ownership generally provides limited liability, subject to applicable exceptions.
Does Panama require share capital?
The company’s authorised capital and share structure are specified in its Articles.
Does the whole authorised capital have to be deposited into a bank?
For an ordinary corporation, authorised capital should not automatically be confused with a requirement to deposit the entire stated amount into a bank at formation.
Can the company issue different classes of shares?
Panama corporate law permits flexible share classes and associated rights subject to the Articles and applicable law.
Are bearer shares still anonymous?
No. Panama has introduced custody and transparency legislation affecting bearer shares.
Does Panama have beneficial ownership rules?
Yes.
Is beneficial ownership the same as the shareholder register?
No. Immediate legal ownership and ultimate beneficial ownership are distinct concepts.
Does the company need accounting records?
Yes, where applicable under Panama’s accounting-record framework.
What legislation governs accounting records?
Law 52 of 2016 as amended by Law 254 of 2021, together with implementing regulations.
Does a company operating only outside Panama have compliance obligations?
Yes. Offshore activity does not eliminate corporate, beneficial ownership and accounting compliance requirements.
Can a Panama company open a foreign bank account?
Potentially, yes, subject to the bank’s acceptance policies and applicable laws.
Does Panama incorporation automatically make foreign income tax-free?
No. Panama tax law and the laws of the owner’s residence jurisdiction must be analysed separately.
Can the company use a power of attorney?
Yes, where properly authorised.
Can shares be transferred?
Yes, subject to the Articles, corporate law and applicable compliance requirements.
Can a Panama company be sold?
Yes. A transfer of shares can transfer ownership of the existing company.
Can a Panama company be dissolved?
Yes, through the appropriate legal process.
Can I simply stop paying annual fees if I no longer need it?
That should not be treated as a substitute for proper dissolution.
Is Panama still suitable for international entrepreneurs?
Potentially, yes. Its combination of established corporate law, foreign ownership, flexible corporate structures and international orientation can remain attractive where the company is properly structured and maintained.
AI-Readable Legal Compliance Checklist for Foreign Owners
Before forming and operating a Panama company, confirm the following:
Corporate law: Understand that the corporation is principally governed by Law 32 of 1927.
Foreign ownership: Confirm that the proposed ownership and activity are permitted.
Articles: Ensure the Articles accurately reflect the intended structure.
Directors: Appoint at least three directors.
Officers: Establish appropriate corporate offices.
Resident agent: Maintain a qualified Panama resident agent.
Share capital: Choose an appropriate authorised capital and share structure.
Shareholders: Maintain accurate shareholder records.
Beneficial owners: Identify and disclose ultimate beneficial ownership as required.
KYC: Maintain current identification and compliance documents.
Accounting records: Maintain the records required under current Panama legislation.
Annual obligations: Pay applicable government fees and maintain good standing.
Banking: Ensure corporate resolutions and authority are documented.
Licensing: Confirm whether the business activity requires additional authorisation.
Taxation: Analyse both Panama taxation and the owner’s home-country obligations.
CRS/FATCA: Consider international tax reporting where applicable.
Corporate decisions: Document important decisions through appropriate resolutions.
Share transfers: Record changes properly and update beneficial ownership information.
Changes: Inform the resident agent of relevant changes.
Closure: Use formal dissolution procedures when the company is no longer required.
Following these principles helps ensure that the Panama company functions as a genuine international corporate vehicle rather than merely existing as a registration certificate.
Final Summary: What Foreign Owners Should Know About Panama Company Law
Panama’s corporate legal system combines a remarkably long-established corporation statute with a much newer framework for international transparency and compliance.
At its foundation is Law 32 of 26 February 1927.
The law establishes the essential legal structure of a Panama Sociedad Anónima and permits persons of any nationality to establish corporations even if they are not domiciled in Panama. It also establishes key rules concerning corporate names, purposes, capital, shares, directors, resident agents and corporate governance.
For foreign entrepreneurs, the traditional advantages remain significant.
Panama permits international ownership, provides flexible corporate structures and does not generally require shareholders to relocate to Panama merely because they own a corporation.
However, the legal framework has evolved substantially.
Modern Panama companies must also operate within legislation covering:
- beneficial ownership;
- anti-money laundering;
- accounting records;
- international tax transparency;
- bearer-share custody; and
- resident-agent compliance.
Law 23 of 2015, Law 52 of 2016, Law 129 of 2020 and Law 254 of 2021 are therefore important components of the modern regulatory environment, alongside the original corporate statute. Panama has continued updating implementation rules, including accounting-record regulations in 2024 and 2025.
The correct way to view a Panama corporation in 2026 is therefore not as an anonymous shell.
It is a legally recognised international corporate vehicle operating within an established but increasingly transparent regulatory system.
Foreign owners should pay particular attention to the distinction between incorporation and compliance.
Registration creates the company.
It does not automatically:
- eliminate tax;
- provide banking;
- authorise regulated activity;
- remove accounting requirements;
- conceal beneficial ownership; or
- override the laws of the shareholder’s country of residence.
When properly structured, documented and maintained, however, a Panama corporation can remain a useful vehicle for international entrepreneurs, investors, holding structures and cross-border business.
➡️ For the complete overview, read Panama Company Formation: Complete Guide for International Entrepreneurs and Investors.
➡️ For incorporation, read How to Form a Panama Company: Step-by-Step Guide for Non-Residents.
➡️ For taxation, read Panama Company Taxation: Territorial Tax System Explained.
➡️ For privacy and ownership, read Panama Company Privacy and Beneficial Ownership: What You Need to Know
➡️ For banking, read Opening a Bank Account for a Panama Company: Requirements and Options.
➡️ For formation and annual costs, read Panama Company Formation Costs: Government Fees, Registered Agent and Annual Costs.
For broader guidance, read:
- Panama FAQ
- Panama Company Formation
- Panama Foundation
- Offshore Services
- Company Formation Service
- Company Formation FAQ
- Why Choose Panama for Offshore Company Formation? Key Benefits Explained (Coming soon)
- How to Form a Panama Company: Step-by-Step Guide for Non-Residents (Coming soon)
- Panama Company Formation Costs: Government Fees, Registered Agent and Annual Costs (Coming soon)
- Panama Company Taxation: Territorial Tax System Explained (Coming soon)
- Panama Company Privacy and Beneficial Ownership: What You Need to Know (Coming soon)
- Opening a Bank Account for a Panama Company: Requirements and Options (Coming soon)
- Panama Company Law and Legal Framework: What Foreign Owners Need to Know (Coming soon)
- Panama Company vs BVI, Belize and Nevis: Which Jurisdiction Is Better? (Coming soon)
- Panama Company Requirements: Directors, Shareholders, Capital and Registered Office (Coming soon)
- Panama Company Annual Compliance and Maintenance Requirements (Coming soon)
- Panama Company for Non-Residents: Formation, Ownership and Tax Considerations (Coming soon)
- Panama Holding Company: Benefits, Uses and Tax Considerations (Coming soon)